The right professional relationship starts with the financial decisions you want help making, not a firm’s name or reputation. Private Wealth Management Firms can offer different kinds of support, so compare each team with your goals, needs, and comfort with sharing decisions. A fiduciary is a professional who must act in a client’s best interest within the scope of the fiduciary relationship.
For individuals and families, the choice can shape how investment, family, and long-term plans work together. We can help you compare the kind of advice relationship you want with the services you need. Trust grows when responsibilities and expectations are clear from the start.
Write down the three financial decisions you most want help with before speaking to an advisor.
Key Takeaways
- Start with the decisions you want help making.
- Match services to your goals and family needs.
- Compare the professionals who would serve your account.
- Review fees, referral incentives, and fiduciary duties.
- Read the agreement before transferring assets.
Which services can a private wealth team coordinate?
A coordinated team can connect investment decisions with retirement, tax, estate, and family priorities. One relationship may bring several experts into the same plan, but the work depends on your needs and the services offered.
Service menus differ, and a family-office label alone does not show which tasks a firm will perform. Ask for a clear list of responsibilities before treating a service as part of your plan.
A family-office label does not tell us which tasks a firm will perform. We need to see the services and responsibilities in writing.
Planning across investments, taxes, and family priorities
Investment management often sits alongside retirement planning, tax optimization, estate planning, trust services, and risk management. A portfolio can support a family’s wider wealth planning when the team understands how each decision affects the others.
Some families also need help with philanthropy, business succession, or planning across generations. These needs may require a team to coordinate with a family’s tax and legal professionals, rather than replace them.
J.P. Morgan’s Family Wealth Services include family engagement and governance, philanthropy, and family-office services. Its stated offerings also include bill pay, private aviation, and cybersecurity.
Match the advice model to the work you need
Automated, hybrid, and traditional advice models differ in service level, client involvement, and ability to handle complexity. The right model depends on how much support you want and how involved you prefer to be.
| Advice model | Typical involvement | Best fit |
|---|---|---|
| Automated | Primarily digital and limited personal interaction | Straightforward needs and comfort managing decisions online |
| Hybrid | Digital tools plus access to a professional | Needs that combine routine support with occasional guidance |
| Traditional | Ongoing professional relationship | Complex planning or preference for regular personal advice |
Think about whether you need regular meetings, help with a specific decision, or ongoing management. A firm may use the same model name as another firm, yet offer a different mix of meetings and services.
Ask who will handle each service you need and how those specialists will coordinate.
How can we compare Private Wealth Management Firms?
A ranking can help build a shortlist, but it cannot tell you which professional is right for your family. Start with the person, then check the team’s experience, approach, and record.
There is no single ranking that answers every client’s needs. Barron’s 2026 ranking covers 250 private wealth management teams, while Forbes’ national 2026 list names 250 advisors.
What wealth rankings measure
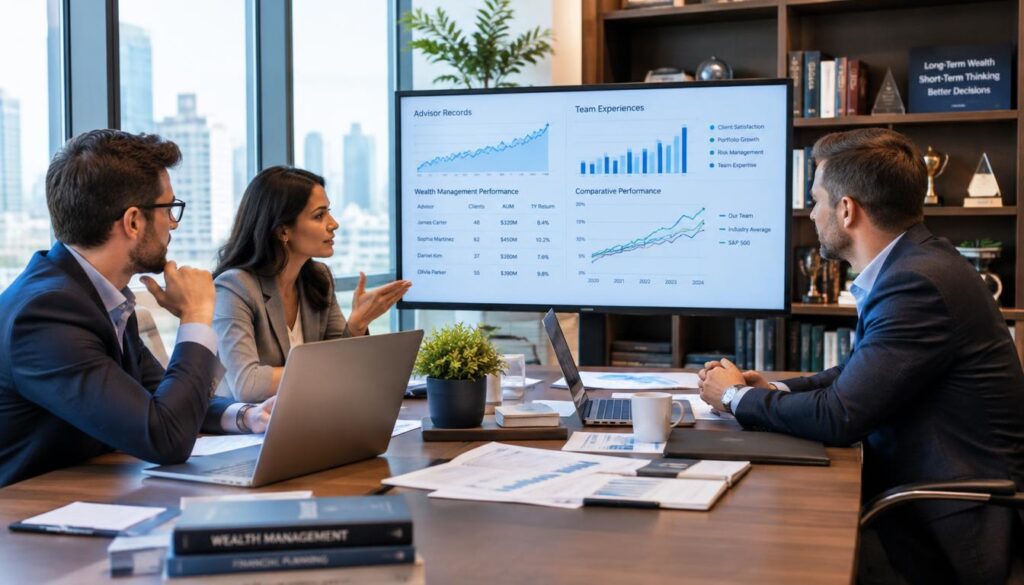
Each list measures different factors, so a high place does not prove that an advisor suits your goals. Barron’s 2026 team ranking weighs team size and structure, regulatory records, member credentials, and resources available to serve clients.
Forbes’ 2026 America’s Top Wealth Advisors list named 250 advisors nationwide. SHOOK Research used interviews, industry experience, compliance records, revenue produced, and assets under management. Both Forbes 2026 national and Best-in-State rankings used data as of June 30, 2025.
J.P. Morgan reported that 533 advisors reached Forbes’ 2026 Best-in-State list and nine reached its national list. Its disclosures say the ratings do not guarantee future success or results, and J.P. Morgan paid a fee for advertising materials after the rating was announced.
Edward Jones states that its Forbes|SHOOK ratings do not measure investment-advice quality, investment performance, or client feedback. It also says it paid to use the ratings, not to obtain them.
Barron’s presents its ranking as a starting point for an advisor search and recommends meeting several professionals and seeking views from multiple third parties. Vanguard’s October 20, 2025 guide advises people to set goals, understand advisor types and costs, check credentials and fiduciary status, then research and interview advisors.
Verify the people behind the ranking
Use rankings as a screening aid, not as proof of future results or a substitute for checking suitability. The NASAA Investment Adviser Guide explains registration, disclosures, conflicts, and fiduciary duties.
Before choosing a professional, check these details:
- Confirm the person’s registration and disciplinary history.
- Verify credentials and experience with needs like yours.
- Ask which team members will serve your account.
- Speak with multiple professionals and independent third parties.
Confirm the individual advisor’s record and role, rather than relying on a firm’s ranking count.
How do advisor fees and referral services work?
A free introduction does not necessarily mean the advisor’s services are free or that every local professional is included. Separate the costs of advice from the costs behind a referral.
An advisor may charge based on assets under management, a flat fee, commissions, or hourly billing. The amount and services included depend on the agreement you sign.
Compare how advisors charge
Ask whether the fee covers planning, portfolio management, or both. A referral service can be free to consumers even when participating professionals pay for advertising or referrals.
SmartVestor is a free service that connects consumers with financial advisors and other investment professionals nearby. Based on ZIP code and local territory, it may introduce a consumer to up to three professionals.
SmartVestor professionals may charge clients through assets under management, flat fees, commissions, or hourly fees. Those advisor charges are separate from what a professional pays to join the referral program.
- How are you paid?
- What services are included in that fee?
- Do you receive compensation for recommending a particular product?
- Does a referral arrangement affect which professionals I can meet?
Understand referral incentives
SmartVestor participants must have at least two years of experience as a registered investment professional. They must work for an investment-advisor or broker-dealer firm not affiliated with Ramsey.
Participants must understand Dave Ramsey’s 7 Baby Steps, agree to the program’s Code of Conduct, and take part in ongoing coaching. These rules set entry requirements, but they do not mean every advisor in a local area participates.
Participants pay a one-time training fee of $3,000, a monthly membership fee of $400, and a monthly territory fee of up to $1,050. Professionals in a select territory may also pay a closed-client fee of up to 25% per year of the gross fees a client pays them.
Ramsey Solutions says program fees are not passed on to consumers, while also disclosing that the fees create a referral conflict. The payments create a financial incentive to refer consumers only to participating professionals.
Ask for the advisor’s complete fee schedule and any referral-related conflicts in writing.
What should we ask before choosing a firm?
A strong fit is a team that can explain who will do the work, how often you will meet, and what happens when your needs change. Look past the firm name to the people assigned to your account.
Check the actual team, access, continuity, and written responsibilities before moving assets. A large firm may offer many points of contact, but your day-to-day experience depends on your assigned team.
Choose a team that can name its responsibilities and explain how your support will change as your needs change.
Match the team to your goals and complexity
Ask which professionals will handle your account and how their roles fit together. A team’s credentials matter, but so does having the right experience for your family’s goals and wealth planning needs.
Find out how often you can meet and whether the team offers in-person, phone, or online meetings. J.P. Morgan Wealth Management had approximately 6,000 advisors and $1.3 trillion in assets under supervision in 2026.
In 2026, J.P. Morgan clients could meet an advisor in person at more than 5,000 Chase branches in the United States. Those figures show scale and access, not a guarantee of advice quality or a fit for every client.
Ask how the team will work with your tax and legal professionals. Check whether the services promised in the engagement agreement match the support you expect.
Check access, accountability, and fiduciary scope
Ask what happens if your advisor leaves and who will take over. You also need to know how the firm tracks decisions, handles questions, and keeps the relationship steady when staff change.
SEC Form ADV describes a firm’s services, fees, and conflicts. FINRA BrokerCheck can help review a professional’s background, while the CFP Board’s planning standards explain when CFP® professionals follow a full planning process.
That CFP® standard does not apply to every advisor or every engagement. Some agreements cover a focused piece of advice and may exclude implementation or ongoing review.
Fiduciary duties apply within the scope of a specific advisory relationship. Confirm whether a particular Vanguard relationship is an advisory service and read its agreement, because fiduciary status depends on the service and relationship.
Use these prompts in a meeting:
- Who is my day-to-day contact?
- How often will we review my plan?
- Who coordinates with my tax and legal professionals?
- What happens if my advisor leaves?
- Which services are fiduciary, and which are not?
Read the engagement agreement and verify the people and services it names before transferring assets.
Conclusion
A sound choice starts with clear goals and a transparent agreement, not a badge or referral alone. The right relationship connects services, costs, responsibilities, and communication to your family’s needs.
Prepare a one-page list of goals and questions, then schedule conversations with more than one advisor. Use each meeting to see whether the team explains its work in plain terms and respects your priorities.
Bring your one-page priorities list to your first advisor meeting and use it to compare the answers you receive.