A sales increase does not affect every company’s operating income by the same amount because companies carry different mixes of fixed and variable costs. The degree of operating leverage (DOL) measures the percentage change in operating income associated with a percentage change in sales. That sensitivity matters when we plan growth, assess risk, or consider an investment.
Fixed costs stay relatively stable as sales change, while variable costs move with activity. A business with costly equipment or infrastructure may gain more from rising sales, yet face more pressure when demand drops. We can use operating leverage and profitability analysis to judge how much income might shift when revenue changes.
We will connect cost structure to profit potential, then test the results against different sales cases. The goal is a practical way to assess whether a forecast leaves enough room for a downturn. We can use the relationship between sales and EBIT to test whether a growth plan leaves enough room for a downturn.
Key Takeaways
- DOL describes how strongly operating income responds to sales changes.
- Fixed costs can boost gains after sales cover them, but raise downside risk.
- Contribution margin shows how sales dollars cover fixed costs and profit.
- Break-even analysis identifies the sales volume needed to cover costs.
- We should compare similar business models and test realistic downside cases.
What Does Operating Leverage and Profitability Analysis Reveal About Cost Structure?
A software business can serve additional customers at low incremental cost after paying for product development, while a consulting firm often adds labor costs as client work grows. That difference shows how cost structure shapes operating leverage and profit sensitivity. Higher operating leverage can raise upside after fixed costs are covered, but it can make falling sales harder to absorb.
Operating costs do not move at the same pace in every company. Telecom networks need large upfront capital expenditures, while an added customer may cost little to serve. When sales fall, the fixed infrastructure still needs funding, which can put pressure on margins.
| Model | Fixed-cost commitment | Incremental cost behavior | What happens when sales fall |
|---|---|---|---|
| Software | Product development | Low cost per added user | Development costs remain |
| Telecom | Network infrastructure | Low cost per added customer | Infrastructure costs remain |
| Consulting | Lower fixed-cost base | Compensation can vary with client hours | Some labor costs can fall |
Consulting firms may have lower operating leverage when compensation varies with client engagements or hours worked. That flexibility can let some costs decline when demand slows. Software and telecom businesses may face more fixed costs, though their added sales can bring more income once those costs are covered.
High operating leverage can widen profit gains after fixed costs are covered, but falling sales can leave those costs exposed.
A contribution margin ratio does not determine DOL by itself. Fixed costs and operating income matter too, because they show how much sales contribution must cover before profit remains. Typical contribution margin ratio ranges on April 15, 2026, were 70-90% for software businesses and 20-40% for retail.
A peer-reviewed study in the Journal of Financial and Quantitative Analysis examines how operating leverage relates to profitability and capital structure. Its findings help explain why operating results and financing choices can interact, though they remain distinct measures. Compare companies with similar business models before treating one cost mix as unusually risky.
How Do We Calculate Degree of Operating Leverage?
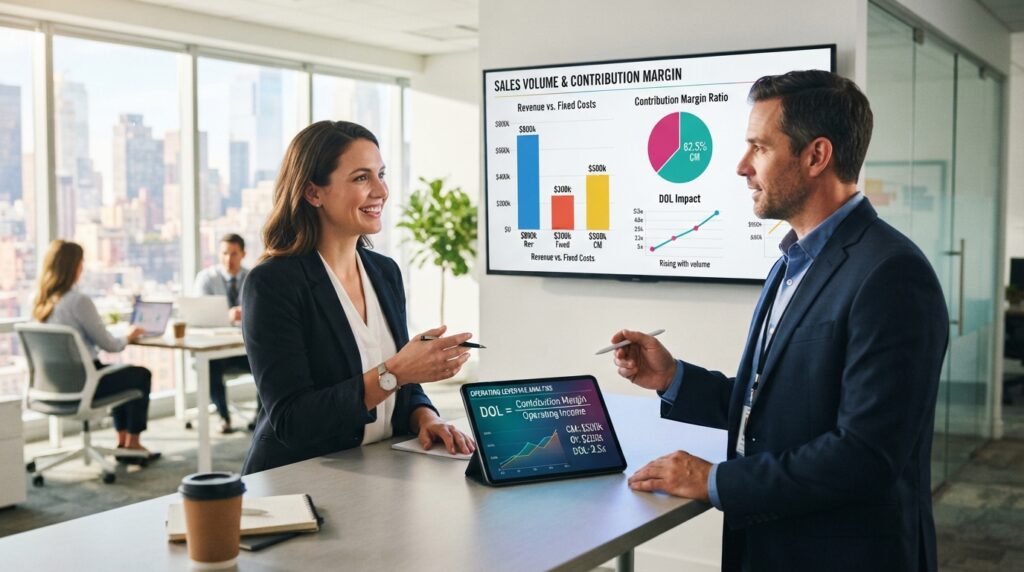
If we know contribution margin and EBIT for the current period, we can calculate DOL by dividing the former by the latter. Current-period figures show how sensitive operating income is at that sales level. Use the starting output’s DOL as an estimate, because the ratio changes as output changes.
DOL has three useful forms. The percentage-change formula divides the percentage change in operating income by the percentage change in sales. We use it to compare two periods when both changes are known.
Choose the DOL formula that fits the available data
The contribution-margin method divides contribution margin by operating income. The output method multiplies quantity sold by contribution margin per unit, then divides by that amount minus fixed costs. Each method estimates operating leverage for a specific sales level.
To calculate DOL from current-period accounting data, we can follow four steps:
- Identify variable costs and fixed costs.
- Calculate contribution margin.
- Calculate EBIT.
- Divide contribution margin by EBIT.
The contribution-margin method is handy when we already have current figures. At 10,000 units sold for $50 each, with $12 variable cost per unit and $100,000 fixed costs, the stated DOL is 1.38. That DOL of 1.38 means each 1% sales change shifts operating income by 1.38% at that output.
Work through a sales-change example
Suppose a company sells 40,000 units for $50 each, spends $30 per unit on variable costs, and has $400,000 in fixed costs. Contribution margin totals $800,000, and EBIT is $400,000. The DOL is 2.0.
A 10% sales increase then raises EBIT by 20%, from $400,000 to $480,000. A 10% sales decrease cuts EBIT by 20%, to $320,000. The same sensitivity works in both directions, so a sales forecast needs an upside and a downside case.
DOL is highest just above break-even and falls toward 1.0 as sales rise. Applying the starting DOL to a later sales change is an estimate, not a promise, because the ratio shifts with output. Recalculate DOL at the current sales level before using it to model another sales change.
How Do Contribution Margin and Break-Even Show Profit Potential?
A product breaks even when its contribution margin has covered all fixed costs, leaving neither operating profit nor operating loss. Each sale first pays variable costs, then helps cover fixed costs. Sales above break-even can produce operating profit when the selling price exceeds variable cost per unit.
We can calculate contribution margin per unit by subtracting variable cost per unit from selling price. The contribution margin ratio divides revenue minus variable costs by revenue. Per unit, the ratio is selling price minus variable cost, divided by selling price.
Calculate contribution margin per unit and as a ratio
A 50% contribution margin ratio means half of each sales dollar can cover fixed costs and generate profit. For example, a product with $1 billion in revenue from 20 million units has a $50 selling price per unit. With $400 million in variable costs, variable cost is $20 per unit and the ratio is 60.0%.
The operating leverage and profitability analysis formula connects contribution margin with operating income. It helps us see how much of each sale remains available to cover fixed costs and support profit. We can also calculate contribution margin from total revenue and total variable costs.
Find the break-even volume
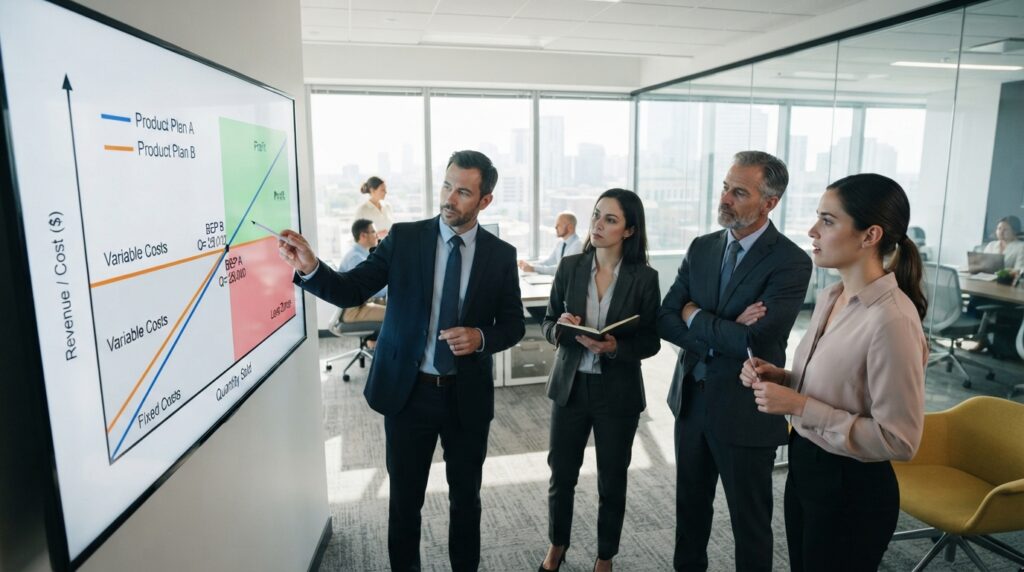
Operating break-even quantity equals fixed costs divided by the selling price per unit minus variable cost per unit. Break-even sales revenue equals total fixed costs divided by the contribution margin ratio. OpenStax’s break-even explanation describes how contribution margin connects sales to fixed and variable costs.
| Metric | Plan A | Plan B |
|---|---|---|
| Unit price | $2.00 | $2.00 |
| Variable cost per unit | $1.50 | $1.00 |
| Fixed costs | $20,000 | $60,000 |
| Break-even quantity | 40,000 units | 60,000 units |
| EBIT at 80,000 units | $20,000 | $20,000 |
An operating leverage and profitability analysis example can compare both plans at the same unit volume. Below 80,000 units, Plan A has higher EBIT; above 80,000 units, Plan B has higher EBIT. At 80,000 units, their EBIT is equal, despite different prices of cost coverage and break-even points.
The table also shows why fixed costs alone cannot settle a plan choice. Plan B has higher fixed costs, but lower variable cost per unit. Round a fractional break-even quantity upward so the plan does not assume sales of part of a unit.
How Should We Use Operating Leverage to Judge Risk and Profitability?
A business with high operating leverage can convert sales growth into stronger margins, but its fixed-cost base can magnify damage when demand falls. Downside testing shows whether the company can withstand a sales shock. We should judge operating leverage alongside demand risk and the costs a company can adjust.
Consider a high-operating-leverage business selling 10 million units at $25 each. Revenue is $250 million, variable costs total $25 million, and contribution margin is $225 million. After $100 million in fixed costs, operating income is $125 million.
That base case has a 50% operating margin and DOL of 1.8x. If unit sales fall from 10 million to 5 million, the operating margin drops from 50% to 10%. The fixed-cost load takes a larger share of the smaller revenue base.
A sales forecast should test what happens when volume falls, not just what happens when growth continues.
Compare upside and downside cases
A low-operating-leverage example has $200 million in variable costs and $50 million in fixed costs. A $50 selling price and $20 unit cost produce a 60% contribution margin. Its costs move more with activity than the high-operating-leverage case.
In the low-operating-leverage example, operating margin rises from 50.0% to 53.3% in the upside case. In the downside case, it falls from 50.0% to 40.0%. The smaller margin swings show how a more flexible cost base can cushion changes in sales.
These examples do not make one cost mix best for every company. A stable sales base may support fixed investment, while uneven demand can make flexible costs valuable. Our analysis should reflect the sales pattern that the business can reasonably expect.
Separate operating leverage from financial leverage
Operating leverage links sales to EBIT; financial leverage links EBIT to shareholder-return measures such as net income, earnings per share, and return on equity. Interest costs affect the second relationship, not operating leverage. A financial statement analysis review can help us check earnings trends alongside cash flow and forecast assumptions.
The financial leverage ratio equals total assets divided by total equity. A company with $2 million in assets and $1 million in equity has a ratio of 2.0. This measure differs from debt-to-equity ratios, which compare debt with equity rather than all assets with equity.
Borrowing can add pressure beyond the operating cost structure. A company may face fixed operating costs and debt payments at the same time, so we should assess those exposures separately. That keeps business risk distinct from financing risk.
Turn the analysis into a management check
We can use a short checklist before approving a growth plan or investment:
- Forecast a sales decline.
- Calculate DOL at the starting output.
- Compare forecast sales with break-even.
- Identify which costs can flex.
- Review borrowing and equity exposure separately.
Each check asks a different question. The decline forecast tests demand risk, while the break-even comparison shows how far sales can fall before operating profit disappears. Cost flexibility tells us which expenses can respond in time.
We should also check whether accounting changes or unusual events distort recent results. Historical trends help frame a forecast, but they do not guarantee future demand. Stress-test a downside sales case before committing to a cost structure that depends on sustained growth.
Conclusion
Operating leverage is most useful when we read it alongside break-even and the company’s ability to adjust costs. Similar business models make better comparisons because their fixed-cost needs and sales patterns are more alike. DOL alone cannot show how much cash a company has or how quickly it can cut spending.
Our next step is to use current-period figures and record the assumptions behind the forecast. A clear downside case can reveal whether expected growth is doing too much work in the plan. Before finalizing a sales forecast, calculate DOL at the current output and test one credible downside case.