A company’s financial reports become more useful when we connect the numbers to the decisions behind them. Financial statement analysis helps us see whether a business is meeting its goals, managing its money, and preparing for growth. We do not need advanced math to begin. Basic reports and simple comparisons can show where results improved, where risks may be growing, and what questions deserve a closer look. The same figures can help an owner plan spending, an investor weigh a business, or a lender judge repayment risk. We will focus on practical steps, clear examples, and checks that keep a single number from telling the whole story. Good analysis links financial results to a real decision. We can start by understanding what each report records and when it records it.
Key Takeaways
- Read the income statement, balance sheet, and cash flow statement together.
- Match each comparison to a clear business question.
- Use ratios as clues, then check their context.
- Compare reported profit with cash movement.
- Record assumptions before using past results to forecast.
What Do the Three Financial Statements Show?
Financial statement analysis uses a company’s reports to evaluate performance, stability, risks, and prospects. It means more than reading numbers; the goal is to support decisions with evidence. Investors may judge whether to buy shares, while creditors weigh repayment risk. Managers use the same reports to set budgets and spot problems.
The three primary reports answer different questions, so read them together. The income statement covers a period, the balance sheet shows one date, and the cash flow statement tracks cash over a period. U.S. public companies file annual Forms 10-K and quarterly Forms 10-Q. Investors who are new to markets can also compare investment platforms for beginners before choosing how to act on what they learn.
Read profit and cash together, because a positive net income does not guarantee cash is available to pay bills.
The income statement reports results over a period
An income statement records revenue, expenses, gains, and losses for a set time, such as a quarter or year. It uses accrual accounting, which records revenue when earned and expenses when incurred, not only when cash moves. Net income shows what remains after reported expenses.
The balance sheet captures one point in time
A balance sheet reports a company’s financial position on a specific date. It lists assets, liabilities, and equity, and follows this rule: Assets = Liabilities + Equity. Assets are what the company owns or controls; liabilities are what it owes. Equity is the owners’ remaining claim.
The cash flow statement tracks cash movements
The cash flow statement groups cash into operating, investing, and financing activities. Operating cash flow covers core business activity; investing includes long-lived assets, and financing includes debt and owner funding. Free cash flow is operating cash flow minus capital expenditures, the cash a company has left after investing in its long-lived assets.
A company can report net profit while running short of cash if customers have not paid their receivables or capital spending is high. Cash timing matters. Read profit and cash together, because a positive net income does not guarantee cash is available to pay bills.
What Is the Right Analysis Process?
A useful analysis starts with a decision to make, not with a ratio to calculate. Begin with the question, such as whether sales growth can support a new location. Then choose data and periods that can answer it. A repeatable process keeps statement analysis focused and makes the result easier to explain.
Use six stages, from defining the purpose to checking what happened after the decision. Collect reliable company data, use consistent periods, and keep a record of any estimates. The three financial statements also help us choose a starting point:
| Statement | Time frame | What it shows | Useful starting question |
|---|---|---|---|
| Income statement | A period | Revenue and expenses | Did profit change? |
| Balance sheet | A point in time | Assets, liabilities, and equity | How is the company financed? |
| Cash flow statement | A period | Cash from operating, investing, and financing activities | Where did cash come from or go? |
Follow a six-stage analysis workflow
- Define the purpose and the decision we need to make.
- Collect the reports and other input data for the question.
- Process the data into useful figures or comparisons.
- Analyze the results and interpret what they may mean.
- Communicate conclusions and recommendations clearly.
- Follow up periodically and update the analysis.
Choose a comparison that fits the question
Trend analysis compares one company over time. We can compare key line items across three to five years to see whether revenue, costs, or cash flow keep moving in one direction. A single year may hide an unusual event, so look for a pattern across periods.
Cross-sectional analysis compares companies at the same point or over the same time range. This approach can help us assess a business against competitors, but the periods must match. A retailer’s holiday quarter should not be compared with another company’s quiet season. Match each comparison to the question, and use a consistent time range when comparing companies.
How Do Financial Statement Analysis Techniques Work?
Horizontal analysis shows how a line item changes across periods, while vertical analysis shows how large each item is relative to a statement base. One tracks change; the other shows structure. A useful technique of financial statement analysis depends on whether we need changes over time, proportional structure, or relationships between figures.
Keep the question and comparison base clear before reading the result. These financial statement analysis techniques help us turn rows of data into useful patterns. They work best when we use the same accounting measures and periods throughout.
Types of financial statement analysis: horizontal and vertical methods
Horizontal analysis, also called period-to-period comparison, compares data across periods. We can calculate percentage changes in revenue, expenses, and profit. Comparing three to five years of key line items can reveal a trend that one quarter cannot show.
Vertical analysis, also called common-size comparison, shows each item as a share of a statement base. On an income statement, we usually compare each item with revenue. On a balance sheet, we compare each item with total assets for the same period.
For a vertical common-size balance sheet, divide each item by total assets for that period and express the result as a percentage. A horizontal common-size balance sheet instead divides each item by its base-year amount. That shows the percentage change from the base year, not its share of total assets.
Ratio analysis connects related figures
Ratio analysis compares related figures, such as current assets and current liabilities. It is the third common technique, alongside horizontal and vertical analysis. A ratio can help us ask whether short-term resources cover near-term bills or whether profit rises with sales.
Each method answers a different question. Horizontal analysis shows changes, vertical analysis shows proportions, and ratio analysis shows relationships between figures. Choose the method that fits the decision, then check the underlying figures before drawing a conclusion.
A change in accounting labels or statement structure can break a comparison even when the math is right. Keep the base consistent across periods so the comparison reflects business changes rather than a change in calculation.
Which Ratios Measure Financial Performance?
We can organize financial ratios into four categories: activity, liquidity, solvency, and profitability. Each category answers a different question about operations, bills, debt, or earnings. The right ratio depends on the decision, and a useful review often uses more than one.
A ratio of 1.0 or more is a general benchmark for current and quick ratios, not a universal target. Industry, cash timing, and business model affect what level makes sense. Use the figures as clues, not grades.
Activity and liquidity ratios
Activity ratios measure operating efficiency. Common examples include inventory turnover, receivables turnover, working capital turnover, fixed asset turnover, and total asset turnover. The cash conversion cycle is a liquidity measure, not a simple ratio. It tracks how quickly a company turns cash into inventory, then turns inventory back into cash.
Liquidity measures short-term payment capacity. The current ratio equals current assets divided by current liabilities. The quick ratio excludes inventory to focus on assets that can more readily cover immediate obligations. Quick assets include cash, accounts receivable, and short-term investments; divide their total by current liabilities.
Cash and receivables can be more useful than inventory when bills come due soon. Still, a high ratio may reflect slow stock or unpaid customer bills. The average collection period measures how many days customers take to pay. Many companies aim for 30 to 45 days, depending on industry. A 1.0 or higher ratio is generally acceptable for current or quick ratios, though needs vary.
Solvency ratios and debt coverage
Solvency measures long-term payment capacity. Debt ratios compare debt or liabilities with assets or equity. The debt-to-equity ratio equals total liabilities divided by shareholders’ equity. Interest coverage and fixed charge coverage test whether earnings can meet financing costs.
A business with heavy borrowing may face greater pressure when sales fall or interest rates rise. Coverage measures add detail because they compare earnings with required payments. We should check whether the company can keep meeting those costs, not just how much debt it carries.
Profitability ratios
Profitability ratios measure profit from revenue and assets. Gross profit margin equals (Revenue − COGS) / Revenue × 100. Operating margin equals Operating Income / Revenue × 100. Net profit margin equals Net Profit / Revenue × 100.
Other useful measures include return on assets and return on equity. Contribution margin equals (Revenue − Variable Expenses) / Revenue. Operating profit ratio equals (Operating Profit ÷ Net Sales) × 100. These measures help us see whether the company earns more from sales, but they do not explain the cause by themselves.
Treat collection-day targets and liquidity benchmarks as starting points, then compare them with the company’s industry and business model.
How Do We Interpret Ratios in Context?
A ratio tells us what a relationship looks like, but not why it reached that level. Context explains the cause, so one ratio or category cannot judge overall performance. A company can report strong returns because it earns more, uses assets well, or carries more debt.
Look at the drivers behind a result before calling it good or bad. DuPont analysis breaks return on equity, or ROE, into parts. A five-component version separates tax rate, interest burden, operating profitability, efficiency, and leverage.
Trace return on equity with DuPont analysis
| Component | What it helps isolate | Main relationship |
|---|---|---|
| Tax rate | Tax burden | Taxes and pretax income |
| Interest burden | Financing cost | Pretax and operating income |
| Operating profitability | Operating margin | Operating income and sales |
| Efficiency | Asset turnover | Sales and assets |
| Leverage | Assets relative to equity | Assets and equity |
These components help us see where a change in ROE came from. Higher leverage can lift returns to owners, but it can also raise risk. A margin shift points to a different driver than a change in asset use. Read the components together, not as five separate verdicts.
Use peer and industry context
Compare like with like. A grocery chain and a software firm use assets differently, so the same ratio can mean different things. Industry-specific measures matter when a factor that drives one business has little meaning in another.
Depending on our question, a useful starter set may include quick ratio, debt-to-equity ratio, net profit margin, earnings per share, and current ratio. The set can help us review liquidity, debt, earnings, and per-share results. It is a starting set, not a scorecard for every company.
When peers report different measures, check how they define each figure and which period they use. Before treating a peer gap as a weakness, check whether both companies use comparable definitions and operate under similar industry conditions.
How Can We Forecast Performance?
A past trend can give us a starting assumption for a forecast, but it cannot promise the same result next period. History is a guide, not a guarantee. Recent growth may slow if costs rise, customers change habits, or the company reaches a limit on capacity.
Build forecasts from stated assumptions, then test how results shift when those assumptions change. A trend in revenue or expenses can set an initial projection. We should note whether it reflects recurring business activity or a one-time event.
Turn historical patterns into a starting forecast
Historical data can help us estimate sales, costs, and cash needs. A company with steady sales growth may use that pattern as a starting point. We still need to ask what could change, such as pricing, input costs, or customer demand.
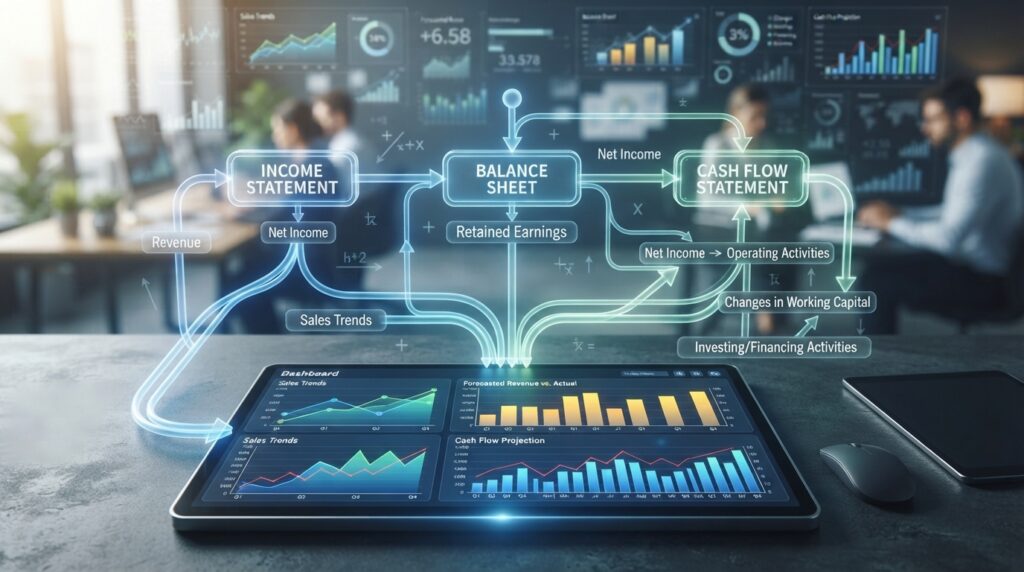
A three-statement model links the income statement, balance sheet, and cash flow statement. It shows how a change in one assumption can affect all three. For example, a sales increase may raise revenue, receivables, and operating cash needs at once.
Test assumptions with scenarios
Sensitivity analysis changes one key assumption at a time, such as sales growth or an interest rate. Scenario analysis combines several assumptions into a case, such as slower growth with higher costs. Simulation tests many possible outcomes using varied inputs.
These tools do not remove uncertainty. They show which assumptions matter most and where the forecast may be fragile. We can compare a base case with more favorable and less favorable cases, then plan for the cash each could require.
A forecast is more useful when we can explain why its figures move. Record the assumptions behind a forecast so we can revisit them when conditions or results change.
What Can Make Financial Analysis Misleading?
A correctly calculated ratio can still mislead when the underlying data no longer describes current conditions. The math may be right, while the comparison is weak. Old reports, broad annual totals, and outside changes can all blur a company’s true position.
Check what changed before treating a ratio as a clear signal. Inflation, interest rates, and shifts in consumer demand can affect companies in different ways. A company may also change its structure or accounting policies, making one period harder to compare with another.
- Stale historical conditions: old data may no longer reflect current costs or demand.
- Seasonality hidden by annual totals: yearly figures can mask busy and slow periods.
- Company structure or accounting-policy changes: reported items may no longer match earlier periods.
- Window dressing through transaction timing: delaying supplier payments can temporarily improve liquidity ratios.
Annual aggregates can hide a cash squeeze that appears during a busy season or before customer payments arrive. A merger or a new accounting policy can also shift reported results without the same change in day-to-day business.
Window dressing deserves a close look at dates. A company that delays supplier payments may show more cash at period-end, while its bills remain due soon afterward. Check for changes in accounting policies and payment timing before treating a sudden ratio improvement as lasting progress.
How Do We Turn Findings Into Decisions?
Mixed results can tell us more than a single headline number when we separate the underlying trend from one-time effects. Kroger’s fiscal year ended February 1, 2025, with net sales down 0.1% year over year and cost of sales down 0.7%. Reported income rose, but adjusted EBIT declined 2.3%.
Separate the reported result from the underlying trend before making a decision. GAAP operating income rose 26.7%, mainly because opioid settlement charges were much lower. Lower cost of sales did not prevent adjusted EBIT from falling, so the figures tell a mixed story.
Compare reported and adjusted results, then identify the main driver before deciding what the change means.
Financial statement analysis notes should record the question, comparison basis, key finding, caveat, and decision implication. A concise record lets us revisit why we reached a conclusion if later results differ.
- Compare reported and adjusted results.
- Identify the main driver of change.
- Check whether cash supports reported profit.
- State the decision and what evidence would change it.
For Kroger, we would avoid calling the higher GAAP result a broad improvement without considering the lower adjusted EBIT. A useful conclusion names the evidence, the caveat, and the next decision it supports.
Conclusion
We make better decisions when we ask what changed, why it changed, and what the evidence supports. Financial statement analysis works best when we connect reports, use fair comparisons, and account for the company’s industry and conditions. A clear finding can still include uncertainty; naming that uncertainty helps us avoid treating one result as a promise.
Our next step can be small and practical. Choose one company and one question, then use its latest reports to build a short, evidence-based conclusion.