A growth plan can stall when the company has not decided how much cash to preserve and which opportunities deserve funding. Our Corporate Financial Strategy connects those ambitions to the company’s ability to pay for them. When leaders want to open a new site, hire more staff, and build a product, they must choose which needs come first. Each choice affects cash flow and the company’s room to respond if sales fall short.
Capital allocation means directing available capital among operating needs, investments, debt repayment, and shareholder returns. A useful approach connects business objectives to financial goals, then uses financial planning to turn those goals into practical choices. We will look at how investment review, cash needs, and regular checks support growth. The aim is not to fund every good idea at once. It is to make clear choices with the money and time we have. A useful strategy makes growth ambitions answerable to the company’s financial capacity.
Key Takeaways
- Link business objectives to clear financial goals.
- Use forecasts to test whether growth plans fit available funds.
- Compare investment choices with the same assumptions.
- Protect liquidity while planning for long-term growth.
- Review results and change course when conditions shift.
What Does a Corporate Financial Strategy Cover?
A company’s financial strategy sets the financial direction that its budgets and forecasts need to support. It tells leaders how finance will serve business objectives, from funding growth to managing risk. Strategy sets direction, while planning turns that direction into targets and actions. Each financial target should support a stated business objective.
Strategy sets the direction, and planning turns it into targets. Every financial target should support a stated business objective.
Financial strategy sets the direction
Financial strategy is the high-level set of financial decisions that supports a company’s goals. It sets priorities for financing, investment, cash, and risk. Corporate finance choices include capital structure, or the mix of debt and equity, along with funding choices and investment risk. These choices shape how much room the company has to act.
Financial management puts that direction into practice. A company may aim to grow while keeping enough cash to handle a weak quarter. Its leaders then weigh the cost of funds, the timing of planned investments, and the risks they can accept. Strategic financial choices should fit the company’s long-term goals, not just its next budget cycle.
Financial planning turns direction into targets
Financial planning turns broad priorities into targets, forecasts, and budgets. It helps teams plan spending, estimate future needs, and compare results with expectations. Corporate financial planning brings together five dimensions:
| Planning dimension | Question it answers | Decisions it informs |
|---|---|---|
| Financial goals | What outcomes matter? | Targets and priorities |
| Forecasts | What may happen next? | Hiring and funding timing |
| Budgets | What can teams spend? | Costs and limits |
| Capital planning | Which long-term needs come first? | Asset and project funding |
| Cash-flow management | When will cash arrive or leave? | Payment and cash timing |
Strategy and planning work together, but they are not interchangeable. Strategy explains the choices a company wants to make; planning tests whether teams can carry them out. Check that each financial target has a clear connection to a business objective.
Which Financial Strategies Support Growth and Resilience?
A company choosing between expanding its own operations, buying another business, and returning cash to shareholders is making a capital-allocation decision. Common choices include organic growth, mergers and acquisitions, debt repayment, dividends, and share buybacks. The right fit depends on the financial goal and the trade-offs leaders accept. Match each use of capital to a stated business goal before comparing its expected return.
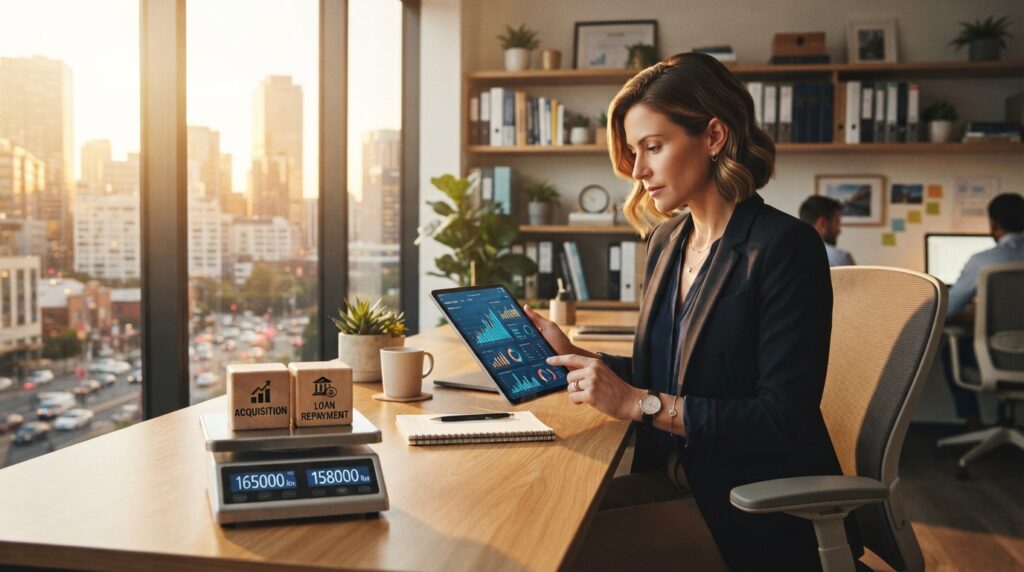
Organic growth uses company resources to build the business from within. It can fund research and development (R&D), expand production or operations, or increase marketing. An acquisition can add products, skills, or customers faster, but leaders need to test the fit and plan for integration. These choices can serve different goals, even within one company.
| Capital-allocation choice | Typical use | Growth or financial goal | Trade-off to examine |
|---|---|---|---|
| Organic growth | R&D, capacity, marketing | Build sales or operations | Time to earn returns |
| Mergers and acquisitions | Buy another business | Gain products or reach | Fit and integration effort |
| Debt repayment | Pay down loans | Reduce debt obligations | Less cash for other needs |
| Dividends | Pay shareholders cash | Return funds to owners | Less capital retained |
| Share buybacks | Repurchase company shares | Return funds to shareholders | Fewer funds for investment |
Consider a manufacturer with popular products and outstanding loans. It could buy equipment to raise capacity, acquire a smaller maker of a similar product, and pay down loans. A financial strategy example is this manufacturer balancing capacity growth, acquisition, and debt reduction. The mix can address demand while reducing debt, but it also uses funds that could serve other needs.
Dividends and share buybacks return cash to shareholders rather than keeping it inside the business. Leaders can compare those choices with company goals, expected returns, and available funds. Match each use of capital to a stated business goal before comparing its expected return.
How Do We Turn Business Goals Into a Financial Plan?
A financial plan becomes actionable when leaders agree on the company’s current position and the outcomes they will prioritize. We can build that plan through five steps, starting with reliable numbers and clear limits. Good planning links business goals to forecasts and decisions teams can carry out. Make assumptions visible so teams can spot when a choice no longer fits.
- Establish a trusted financial baseline and constraints. Confirm cash, obligations, existing commitments, and limits on funding.
- Set priorities tied to business objectives. Name the outcomes leaders will fund first and explain why.
- Forecast key drivers under more than one operating condition. Include volume, pricing, headcount, and capacity in each forecast.
- Allocate resources and set decision rights. Make clear who can approve spending and when leaders must review a choice.
- Operationalize the plan and review it continuously. Give teams targets, owners, and a way to report changes.
Different planning forms answer different needs. Strategic planning sets long-term direction and links major goals to resources. Operational planning turns those goals into team plans, costs, and timelines. Both help managers connect the company’s objectives to day-to-day work.
Cash-flow and liquidity planning focuses on whether funds will arrive in time to meet near-term obligations. Scenario and contingency planning tests what leaders might do if sales, costs, or other conditions change. Together, these forms help us plan for expected work and prepare for setbacks without treating one forecast as certain.
Forecast assumptions should reflect the business drivers that shape results. A sales forecast, for example, may change when volume or pricing shifts. Staffing plans depend on headcount and capacity, while planned investment can alter both. Make the planning assumptions visible so teams can tell when a decision no longer fits the agreed direction.
How Should We Evaluate Investments and Allocate Capital?
Before funding a project, we should be able to say what it is expected to achieve and what changes if we approve it. We can compare a proposal’s benefits, costs, alternatives, and risks before committing scarce capital. A shared test makes it easier to judge projects on equal terms. Use the financial result to inform judgment, not replace it.
Test the project’s benefits, costs, and risks
Start with the benefit the project should create. Ask whether another option could produce the same result with less cost or risk. Then decide which benefits can be measured, such as added output or lower operating costs. A clear goal helps us judge whether the project did its job.
Count incremental costs: the expenses that change because we approve the investment. These may include equipment, staffing, training, or ongoing support. Test project risks, too, including delays, lower demand, and cost increases. A forecast can show how those changes affect the expected result, but it cannot predict every outcome.
When company finances also affect an owner’s future, succession planning deserves separate attention. A business succession plan can address potential successors, business value, liquidity needs, and tax and estate coordination. A sale, family transfer, or management handoff can bring different cash-flow and tax effects.
Match the funding mix to the company’s capacity
Capital budgeting evaluates long-term investments, such as equipment or major projects. Capital structure management concerns how the company funds its needs through debt and equity. Working capital management focuses on near-term operating needs, including the timing of cash coming in and going out. Each technique addresses a different financial decision.
Value-based management asks whether a decision creates value after accounting for the capital it uses. That view can help us compare projects that have different costs or timelines. A strong forecast matters, but leaders should also weigh business fit, timing, and risk. Compare proposals using the same assumptions and risk lens, then document why the selected option best serves the company’s objectives.
How Do We Protect Cash Flow and Adjust as Conditions Change?
A profitable plan can still create strain if cash arrives later than the company’s bills are due. Liquidity means cash available to meet near-term obligations while retaining flexibility. Timing matters because profit measures alone may not show when money is available. Set an advance decision trigger for material changes in demand, costs, or cash timing.
Profit does not show when cash will arrive. Track timing so the company can meet near-term obligations and respond to change.
Working capital planning covers receivables, payables, and inventory. Slow customer payments can delay cash coming in, while bills may fall due sooner. Inventory can tie up cash before products sell. Cash-flow forecasts bring these timing pressures into view and help us plan around them.
Teams can use this checklist during performance reviews:
- Review revenue and demand signals.
- Check margin and cost movement.
- Monitor cash timing and working capital.
- Agree on triggers to pause, resize, or reallocate funding.
Financial forecasts, performance-management data, and specialist analysis can inform capital-allocation decisions. Gross margin can show how much revenue remains after direct costs. Return on investment can help compare results with the money used. The cash conversion cycle can show how long cash stays tied up in operations.
These measures tell different parts of the story. A healthy margin does not guarantee that customers pay on time, and a positive investment return does not remove cash pressure. We should review the signals together and check whether current conditions still support planned spending. Set an advance decision trigger for material changes in demand, costs, or cash timing.
Which Careers and Learning Paths Use Corporate Finance Skills?
Corporate finance careers use strategic judgment to connect financial analysis with decisions about a company’s resources. Relevant roles include CFO, controller, financial analyst, FP&A manager, treasurer, and investor relations manager. The work varies by organization, team size, and business needs. Choose training that fits the work you want to do.
Corporate finance roles vary by organization. Choose learning that fits the responsibilities you want to take on.
Roles across corporate finance
A CFO leads financial direction, while a controller often oversees accounting and financial reporting. Financial analysts study results and support decisions with forecasts and other analysis. FP&A managers lead financial planning and analysis work, helping teams link plans with performance.
Treasurers often focus on cash, funding, and financial risk. Investor relations managers communicate company information to investors and support those relationships. Responsibilities differ by organization, so job titles do not always signal the same duties. Corporate financial strategy jobs can sit in finance leadership, analysis, treasury, or investor relations.
Courses, credentials, and degrees
Courses can build skills in finance, corporate strategy, or management without serving as a job requirement. A course-completion credential shows that a learner finished a course. A professional certification is a separate credential tied to a professional program or body. A degree focused on corporate financial strategy is not the only route; finance, accounting, or business degrees can support related careers.
The University of Chicago Corporate Financial Strategy course runs for eight weeks, costs US$2,800, and provides 4 CEUs on successful completion. Coursera’s 2026 corporate finance course page lists financial analysis, capital budgeting, risk management, and valuation techniques as possible topics. The page does not assign a price to the course.
A course may suit someone who wants focused study, while a degree can offer broader academic work. The right choice depends on the skills a role needs and the learner’s time and goals. No course or credential is required for every finance job. Choose learning by comparing its subject matter, time commitment, and credential with the responsibilities you want to take on.
Conclusion
A sound financial strategy gives us a disciplined way to pursue growth without losing sight of cash and risk. It ties business objectives to realistic funding, measurable financial goals, and regular review. That link helps leaders decide which plans the company can support and what evidence would call for a change.
We can start with a simple working list: current priorities, available resources, and assumptions most likely to change. Include the sales, cost, or timing beliefs behind each major plan. Clear assumptions make it easier to see when the company’s financial position no longer supports the choice.
Growth does not require us to fund every opportunity at once. It requires choices that fit the company’s capacity and room to adjust when conditions shift. Set a leadership review to agree on the company’s top financial priority and the evidence that will show whether it is working.