A business can make a promising investment and still weaken its value if the return does not compensate for the capital it uses. Cost of Capital Estimation Methods help us compare expected returns with what investors and lenders require. The weighted average cost of capital (WACC) is the average required return across a company’s financing sources, weighted by each source’s share of its capital.
A sound estimate helps us judge risk, compare funding choices, and make better investment decisions. It is a benchmark, not a promise that a project will earn a certain amount. We can use it to ask whether expected gains fit the risks and costs facing our company in the market. A useful estimate starts with the financing sources the business actually relies on.
Key Takeaways
- Compare a project’s expected return with the return required by its capital providers.
- Estimate the cost of each funding source before blending them into WACC.
- Use market values when setting capital weights, when those values are available.
- Match the discount rate to the cash flow being valued.
- Record the assumptions and review them when risk or financing changes.
What Does Cost of Capital Tell Us About a Business Decision?
A business uses its required return as a hurdle for judging whether a project’s expected payoff justifies its risk. A project that beats the right benchmark may support investment, while one below it needs closer review.
Suppose a bakery owner estimates a 14% cost of equity and considers investing $50,000. A second location is projected to return 10%, while wholesale sales are projected to return 18%. Wholesale sales clear the 14% benchmark, but the second location falls short.
A projected return above the required return can support an investment, but it cannot settle the decision by itself.
The comparison is a starting point, not a full verdict. Forecast risk may differ between a new storefront and a wholesale contract, and cash-flow timing can change the value of each option.
In financial management, a useful working note keeps the required return, expected project return, and key assumptions together. We can include the estimate date, sales forecast, major costs, and the risks that could change results.
That note gives owners and investors a clear basis for discussing decisions. It also helps us spot when a new forecast no longer fits the assumptions behind the original estimate. Compare projects using the same time horizon and consistent assumptions before choosing one.
Which Cost of Capital Estimation Methods Fit Each Funding Source?
A company’s overall financing rate comes from weighting each funding source’s required return by its portion of capital. WACC combines debt, common equity, and preferred stock when the company uses those sources. Each source’s cost is multiplied by its share of total capital, then the weighted amounts are added.
This average cost capital method creates one benchmark for the company’s financing mix. It works only when we estimate source costs and weights on a consistent basis.
Estimate the required return for each source
Debt uses the company’s borrowing rate, adjusted for tax effects when applicable. Common equity uses the return shareholders require, while preferred stock uses its dividend yield.
The source’s financing cost reflects different claims on the company. Interest-bearing debt has a tax adjustment, but common equity and preferred dividends do not receive that interest deduction.
Blend source costs into WACC
The WACC formula multiplies each source cost by its capital weight, then adds the results. In plain terms, the weighted average cost reflects how much debt, equity, and preferred stock each contributes to total capital.
An IESE Business School working paper explains WACC’s use with firm cash flows and notes common valuation errors.
| Funding source | Cost-estimation basis | Capital weight | Tax treatment |
|---|---|---|---|
| Debt | Current borrowing rate | Debt value ÷ total capital | Apply after-tax adjustment when interest is deductible |
| Common equity | Expected return required by shareholders | Equity value ÷ total capital | No interest tax adjustment |
| Preferred stock | Annual dividend ÷ current market price | Preferred value ÷ total capital | No interest tax adjustment on dividends |
Preferred stock cost is its annual dividend divided by its current market price. If a company has no preferred shares, that source has no weight in its capital structure.
Use the costs that fit the company’s current funding, rather than treating every company as if it uses the same mix. Check that all source weights together equal 100% before interpreting the blended rate.
How Do We Estimate Cost of Equity With CAPM?
CAPM turns a risk-free return, market premium, and beta into an estimate of what equity investors require. The capital asset pricing model links expected return to broad market risk. Keep the risk-free rate and market premium in the same currency.
The model is useful when we can form a reasonable view of market risk and the company’s beta. Its inputs should reflect the company and the date of the estimate, not an old market snapshot.
Set the risk-free rate and market premium
A long-term government bond yield is a suitable risk-free rate for estimating cost of equity. For a U.S.-dollar estimate, use the U.S. Treasury bond rate minus the U.S. default spread.
The equity risk premium (ERP) is the market’s extra expected return over a risk-free investment. For U.S. estimates, the U.S. ERP is the implied S&P 500 return minus the U.S.-dollar risk-free rate.
The implied S&P 500 return is the rate that makes the index level equal the present value of expected dividends and buybacks. The U.S. equity risk premium calculation uses that expected market return after subtracting the risk-free rate.
For mature markets, the ERP is the U.S. ERP minus the U.S. default spread. That adjustment helps keep the market premium tied to the country risk reflected in the estimate.
Estimate beta and apply CAPM
Beta measures a stock’s exposure to broad market movements. A beta above one signals greater market sensitivity than the broad market, while a beta below one signals less sensitivity.
CAPM estimates cost of equity as risk-free rate plus beta multiplied by ERP. With a 4.3% risk-free rate, a 1.20 beta, and a 6.0% ERP, expected market return is 10.3%.
The cost of equity is 4.3% + 1.20 × 6.0%, which equals 11.5%. That rate is an expected return, not a guaranteed payout to shareholders.
- Select a long-term government bond yield.
- Estimate the market premium in the same currency.
- Use a beta that matches the company’s financing and business risk.
These checks help us keep CAPM inputs tied to the company being valued. Keep the currency and date consistent across the risk-free rate and market-return assumptions.
How Can We Estimate Beta for a Private Company?
A private company can estimate beta by borrowing market evidence from comparable public businesses and adjusting it to fit its own financing. This gives us an equity risk estimate even when the company has no traded shares. Comparable business risk matters more than company size alone.
The resulting beta helps reflect how the private company’s equity may respond to broad market changes. It is an estimate, so the firms we choose and the adjustments we make both matter.
Unlever and relever comparable-company betas
First, select public companies with similar products, customers, and business risks. Their observed betas include the effect of their own debt and equity mix.
Unlevering removes that financing effect to estimate business risk without debt. We can then relever the result using the private company’s debt-to-equity ratio, so the estimate reflects its own capital structure.
When debt beta is zero and debt has a tax benefit, levered beta equals unlevered beta × [1 + (1 − corporate tax rate) × debt-to-equity ratio]. This formula assumes debt itself has no market-risk exposure.
A comparable-company beta method lets us use public market evidence while adjusting for the private firm’s financing. The debt-to-equity ratio must match the company’s intended or current financing mix.
Adjust for leverage and business mix
More financial leverage raises a company’s equity beta because debt adds fixed payment obligations. That makes shareholders more exposed to changes in operating results.
A company with several business lines also needs a business-risk blend. Its beta reflects the weighted average of its business-line betas, based on each line’s share of the company.
For example, a firm with a large retail operation and a smaller software unit should not use either unit’s beta alone. Their relative business weights shape the company-level estimate.
We should revisit the business mix when a company adds or sells a major operation. Use comparables with business risks that resemble the private company, not just companies of a similar size.
When Do Dividend and Build-Up Methods Fit Better?
A stable dividend payer may estimate equity cost from its next dividend, share price, and expected growth. Dividend growth fits best when payouts are regular and predictable. Use this method only when a steady growth rate is a fair assumption.
A private company with no stable dividend may need a build-up estimate. This approach adds risk premiums to a starting rate, but judgment plays a larger role.
Use dividend growth for stable payouts
The dividend-growth formula is cost of equity = next year’s expected dividend ÷ current share price + expected dividend growth. It assumes dividends grow at a steady rate over time.
With a $50 share price, a $2 expected next-year dividend, and 3% growth, the estimate is $2 ÷ $50 + 3%, or 7%. The result can be misleading if dividends do not track the company’s earning power.
The CFA Institute’s dividend valuation guidance explains the constant-growth model and when stable dividend patterns make it useful.
Build up risk premiums for private firms
A build-up estimate starts with a risk-free rate and adds an ERP, then relevant industry, size, and company-specific adjustments. It can suit private firms when public share data offers a poor match.
A small-company size premium may fall in the 3%-5% range. Company-specific risk adjustments may range from 0%-10% or more, depending on the risks judged relevant.
Those ranges are inputs for judgment, not fixed rates that every small business should add. A thin customer base, for example, may raise company-specific risk, while stable contracts may support a lower adjustment.
We should write down why each premium applies and avoid turning a rough estimate into a false-precision number. Do not add a risk premium twice if the chosen ERP or company adjustment already captures the same exposure.
How Do We Estimate the Cost of Debt and Preferred Stock?
Use the rate the business would face on current borrowing, not an old loan rate that no longer reflects its financing conditions. Current loan rates and bond yields help us estimate the cost of debt. Use the after-tax cost of debt when interest tax effects apply.
Debt evidence can come from the company’s own borrowing or similar debt in the market. Preferred stock uses a different measure because its dividend is not interest.
Estimate debt from loans, bonds, and proxies
For bank loans, review the current interest rate and terms. For bonds, use the current yield to maturity, which reflects the return implied by today’s bond price and future payments.
If the company has no direct borrowing data, yields on comparable debt can serve as a proxy. Choose debt with similar credit risk and terms, rather than borrowing a rate from a very different borrower.
| Evidence to collect | Rate to use | When the method fits |
|---|---|---|
| Current bank loan rate and loan terms | Current interest rate | Company has an active bank loan |
| Bond price, coupon, and maturity | Current yield to maturity | Company has publicly traded bonds |
| Yields and terms for similar debt | Comparable debt yield | Company borrowing data is limited |
After-tax cost of debt equals the borrowing rate multiplied by (1 − corporate tax rate). For example, a 5% borrowing rate with a 30% tax rate gives an after-tax cost of 3.5%.
Calculate preferred stock cost from its dividend
Preferred stock cost equals its annual dividend divided by its current market price. A $4 annual dividend on preferred shares priced at $50 gives an 8% cost.
Interest on debt may lower taxable income when it qualifies for a deduction. Preferred dividends are distributions to investors, not deductible interest. Apply the tax adjustment only to interest-bearing debt, not to equity distributions.
Which Capital Values Should We Use for WACC Weights?
Calculate each capital weight by dividing that source’s value by total capitalization. Market values are preferred for a forward-looking estimate because they reflect current investor pricing. Use market values for debt and equity when they are available.
In the basic debt-and-equity case, D means debt value, E means equity value, and total capitalization is D + E. Debt weight equals D ÷ (D + E), while equity weight equals E ÷ (D + E).
Suppose a company has $100 billion in market value of equity and $25 billion in net debt. Total capitalization is $125 billion, so equity carries an 80% weight and debt carries a 20% weight.
These percentages describe the funding mix used in the weighted average cost estimate. If preferred stock is part of the company’s financing, its value also belongs in total capitalization.
Market debt value may be hard to find for a private company or a loan that does not trade. Book debt can serve as a practical proxy when market value is unavailable and book value remains close to it.
Book equity may not reflect what investors would pay for a company’s shares today. For that reason, market equity usually gives a better view of current capital value.
Keep each weight tied to the same total capitalization, rather than dividing debt and equity by different bases. Confirm the debt and equity weights sum to 100% before using them in WACC.
How Do We Calculate Cost of Capital in Excel?
A spreadsheet can calculate WACC once each funding source has a cost, a tax treatment, and a weight. We can make the calculation easy to audit by keeping each input in its own column. Multiply each source’s weight by its applicable after-tax cost, then add the contributions.
Set up fields for funding source, pre-tax cost, tax rate, after-tax cost, market-value weight, and weighted contribution. Use a tax adjustment for debt when applicable, but not for equity distributions.
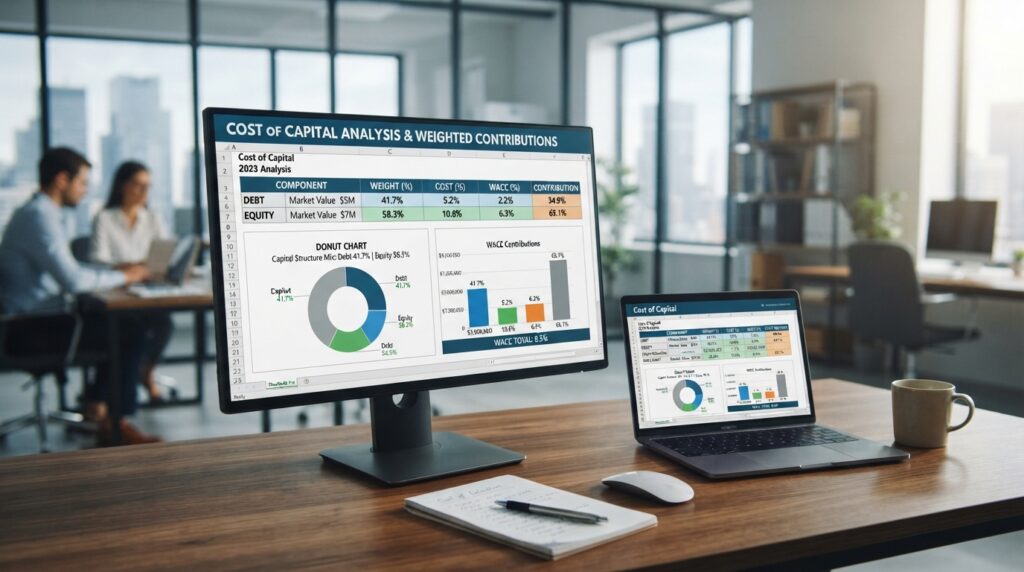
A simple Excel workflow for a cost of capital estimation methods calculator is:
- Enter each funding source and its pre-tax cost.
- Enter the tax rate and calculate after-tax debt cost.
- Enter each market-value weight and calculate its contribution.
- Sum the weighted contributions to get WACC.
For example, the debt formula is borrowing rate × (1 − tax rate). The contribution formula multiplies the source weight by its after-tax cost, where the tax adjustment applies.
| Funding source | Cost used | Weight | Weighted contribution |
|---|---|---|---|
| Equity | 9.2% | 60% | 5.52% |
| Debt | 3.5% after-tax | 40% | 1.40% |
| Total | WACC | 100% | 6.92% |
In the EcoFurnishings example, a 5% loan rate and 30% tax rate produce a 3.5% after-tax debt cost. Equity represents 60% of capital, and debt represents 40%.
With a 9.2% cost of equity, equity contributes 5.52% and debt contributes 1.40%. Their sum is a 6.92% WACC, the average cost capital for this example.
We can add notes beside cells to explain where each assumption came from. Keep the input assumptions visible beside the formula so the result can be checked and updated.
How Should We Apply and Maintain the Estimate?
Use the rate that matches the cash flows being valued, or the valuation can compare unlike claims. WACC discounts unlevered free cash flow to the firm (FCFF), while cost of equity discounts levered free cash flow to equity (FCFE). When a company has no debt, its cost of capital and cost of equity are equivalent.
FCFF is cash available to debt and equity investors before debt payments. FCFE is cash left for common shareholders after debt payments and other financing needs.
A higher discount rate lowers the present value of future cash flows, all else equal.
The company-wide WACC fits projects with risk close to the company’s usual business risk. A project with much higher or lower risk may need a rate that reflects its own exposure.
We should review the estimate when its key inputs change. A dated record helps us track why the rate moved and which assumptions changed.
- Market rates: review after changes in government bond yields or current borrowing rates.
- Financing mix: update the estimate when debt, equity, or preferred stock weights change.
- Business risk: revisit it after a new business line or major operating shift.
- Project forecasts: revise the decision when expected cash flows or their timing change.
For each update, save the input values, the estimate date, and a short note on revisions. That record is useful when we compare an old investment decision with current results.
Owners who need help reviewing complex financing choices can compare financial advisor services and fees. We should also check who handles each task and how the adviser works with a CPA or attorney.
A written scope can clarify responsibilities before a major decision. Our guide to comparing wealth management firms covers experience, fees, conflicts, and service terms.
Revisit the assumptions whenever financing or business risk changes enough to alter the return investors require.
Conclusion
A useful cost-of-capital estimate makes financing assumptions explicit before a business commits funds. It gives us a decision benchmark, not a guarantee that a project will meet its forecast or create value.
Use current assumptions that match the financing and risk being evaluated. Before assessing a major investment, record the company’s current funding mix and the date of each input.
That simple record makes later reviews clearer and helps us see which beliefs shaped the decision. Record the inputs and review them with a qualified financial adviser when the investment or financing decision is complex.