In 2025, 87% of American mortgage borrowers did not choose the most competitive rate available. A refinance can help when a new loan better fits your budget or payoff goals, but the advertised rate alone cannot show whether it is worthwhile.
We can help you compare options for lowering your monthly payment, reducing total interest, paying off the loan sooner, or accessing home equity. A national average offers a useful starting point, but it is not a personalized refinance quote.
Your credit score, loan details, and costs all affect the money you may save or spend. We can help you compare personalized options against the goal that matters most to you.
Key Takeaways
- Compare offers based on the same loan amount and term.
- Consider total loan costs, not just the interest rate.
- Check whether monthly savings can recover refinance costs.
- Choose a loan term that fits your budget and payoff goal.
- Compare personalized refinance quotes with our team.
Compare offers using the same loan amount and term so the cost differences are clear.
How to Compare the Best Mortgage Refinance Rates
The national 30-year refinance benchmark was 7.39% on October 23, 2026, while Freddie Mac’s 30-year fixed average was 7.32% the day before. These different measures can help frame a search, but neither guarantees the interest rate a lender will offer you.
Bankrate’s national refinance average and Freddie Mac’s weekly survey track different loan categories. Compare the loan type, term, date, and APR before judging two rates. APR means annual percentage rate, a measure that includes the interest rate and certain loan costs to help compare offers.
National averages are reference points, not personal offers. Compare APRs for the same loan amount and term.
| Benchmark | Loan term | Rate | Date or comparison |
|---|---|---|---|
| Bankrate refinance average | 30-year | 7.39% | October 23, 2026 |
| Freddie Mac fixed average | 30-year | 7.32% | October 22, 2026 |
| Freddie Mac fixed average | 15-year | 6.68% | October 22, 2026 |
Freddie Mac’s 30-year average fell from 7.40% the prior week, but stood above its 6.19% average a year earlier. Its 15-year average fell from 6.71% the previous week, but rose from 5.44% a year earlier.
Freddie Mac’s weekly mortgage-rate survey reports national averages drawn from mortgage applications. Use the dated comparison as a snapshot, not as a promise about a future quote.
Current refinance mortgage rates include the 7.39% Bankrate benchmark dated October 23, 2026. Interest rates today for a 30-year fixed mortgage include Freddie Mac’s 7.32% average dated October 22, 2026.
Personalized rates depend on borrower and loan details, while APR also reflects certain costs. Treat any national average as a reference point, then compare personalized APRs for the same loan amount and term.
When Might Mortgage Rates Go Down?
The Mortgage Bankers Association expects 30-year mortgage rates to remain above 7% throughout 2027, so a quick return to much lower rates is not its forecast. That outlook is a forecast, not a promise about what rates will do.
No one can name a reliable date when mortgage rates will go down to a particular level. Waiting for a hoped-for rate can mean paying more in interest meanwhile. The MBA Refinance Index was down 59% compared with a year earlier.
Mortgage rates can shift as inflation changes, bond yields move, economic conditions develop, and the Federal Reserve makes decisions. The Fed does not set mortgage rates directly, but its policy can affect markets that help shape borrowing costs.
Four influences can push rates up or down:
- Inflation: faster price growth can put upward pressure on rates.
- Bond yields: mortgage rates often move with bond-market changes.
- The Federal Reserve: policy decisions can affect market expectations.
- Economic uncertainty: shifts in confidence can move bond yields and rates.
These forces can change at different speeds, so a forecast may not match the rate available when you apply. A rate prediction cannot replace a quote based on your loan and borrower details.
Compare a refinance that works at today’s quote with the cost of waiting, rather than relying on a rate-date prediction.
What Determines Your Personalized Refinance Rate?
A strong credit profile can support a lower offer, but lenders also price the property, equity and loan structure. Your profile matters because lenders estimate how likely a loan is to be repaid.
FICO credit scores range from 300 to 850. Lenders commonly review credit history, debt-to-income ratio, loan-to-value ratio, occupancy, and loan type. Those details can lead two applicants seeking the same advertised loan to receive different offers.
Credit profile and debt obligations
Your credit history shows how you have handled borrowing and payments. A lender may view missed payments or high debts as added risk, which can affect the interest rate or terms offered.
Debt-to-income ratio compares monthly debt payments with gross monthly income. Lenders may consider the full picture, including your income, monthly obligations, and history of paying debts.
Equity, occupancy and loan type
Loan-to-value ratio compares the loan balance with the home’s value. More home equity can affect pricing, while the home’s use and property type may also shape the offer.
A primary home, a second home, and an investment property can carry different risks for a lender. A fixed-rate loan and an adjustable-rate mortgage can also have different pricing.
A lender’s advertised rate assumes a particular borrower and loan setup. Check your credit report for errors before requesting quotes, because correcting an error may improve the profile lenders review.
Why Compare Refinance Lenders Instead of Taking the First Offer?
Comparing offers matters because a borrower can qualify for a better rate than the first lender presents. One quote is not a market check, and the lowest advertised rate may not carry the lowest total cost.
Bankrate found that 87% of American mortgage borrowers did not choose the most competitive rate available to them in 2025. Those borrowers paid an average of $3,343 extra per year. That finding shows how costly it can be to accept an offer without comparison.
Compare the cost, not just the rate
Freddie Mac estimates that comparing two lenders may save borrowers up to $600 a year. Comparing four lenders may save up to $1,200 a year. These are possible savings, not guaranteed results or the same measure as Bankrate’s 2025 findings.
| Number of lenders compared | Possible annual savings | What the comparison means |
|---|---|---|
| 2 lenders | Up to $600 | Check two competing offers |
| 4 lenders | Up to $1,200 | Check four competing offers |
Make competing quotes comparable
Ask each lender to price the same loan amount, term, rate structure, points, and occupancy. Otherwise, a lower rate could reflect a shorter term, more points, or a different loan setup.
Look at lender fees alongside the interest rate. A quote with a lower rate may charge more upfront, while another may show a higher rate and lower fees.
Request multiple quotes on the same terms before deciding that the first offer is competitive.
How Do You Calculate the Refinance Break-Even Point?
Divide your total refinance closing costs by your monthly savings to estimate the number of months before the costs are recovered. That time is the break-even point.
Break-even point in months = closing costs ÷ monthly savings. If closing costs are $8,000 and monthly savings are $225, the break-even point is 35.56 months.
Refinance closing costs typically run 2%-5% of the loan amount. For a $300,000 loan, that is typically $6,000-$15,000 in costs. The break-even calculation uses your own costs and payment savings.
Divide costs by monthly savings
Use the principal-and-interest payments on your current mortgage and the proposed loan. Subtract the new payment from the old one to estimate monthly savings.
A refinance calculator can estimate the break-even point, but the result depends on the figures entered. Use actual quotes for costs and payments, rather than a broad estimate.
- Closing costs for the new loan.
- Current and proposed monthly principal-and-interest payments.
- How long you expect to stay in the home.
- Any prepayment penalty on the current mortgage.
Check how long you expect to keep the home
Refinancing is more likely to make financial sense when you keep the home beyond the break-even point. Selling or refinancing again sooner may leave some costs unrecovered.
Refinance only if your expected time in the home extends beyond the calculated break-even point and the wider loan costs still fit your goal.
Is the 2% Rule a Reliable Refinance Test?
The 2% rule is a rough screen, not a hard requirement for refinancing. It suggests that a new rate should be at least two percentage points below the current rate, but your costs decide whether a loan makes sense.
Some guidance uses a 0.75-percentage-point rate reduction as a rule of thumb for offsetting standard closing costs. Neither threshold works for every borrower or loan. Your costs, monthly savings, and time in the home can change the result.
Treat the rule as a starting point
A borrower may benefit from refinancing with a smaller rate drop if costs are low and the new loan fits a long-term goal. A larger rate drop may still disappoint if fees are high or the borrower moves soon.
The old loan’s balance and remaining term also shape the comparison. A lower interest rate alone does not show how much interest you will pay over the full loan term.
Weigh discount points against the rate reduction
A discount point costs 1% of the loan amount upfront and typically lowers the interest rate by about 0.25 percentage points. The 2% rule cannot account for that choice on its own.
Points may make sense when the lower monthly payment recovers their upfront cost during the time you expect to keep the loan. A borrower who moves or refinances sooner may not recover that cost.
Compare the upfront point cost with the monthly savings over the time you expect to keep the loan.
Should You Choose a Shorter or Longer Refinance Term?
A 15-year refinance usually pays the balance off sooner, while a 30-year term can reduce the monthly payment. The right fit depends on the payment your household can manage and how much interest you want to pay.
A longer term can lower the monthly payment but increase total interest over the life of the loan. It may also restart the repayment clock, even if the new interest rate is lower.
A 15-year term typically brings higher monthly payments, since the balance must be repaid faster. It may help borrowers who can afford the larger payment and want to own the home free of a mortgage sooner.
A 30-year term spreads payments over a longer period. That can ease monthly cash flow, but the borrower may pay interest for more years than under the current mortgage.
Compare these three details before choosing:
- Years remaining on the current mortgage.
- Total interest under each loan option.
- The monthly payment your household can sustain.
Use the same loan amount and rate assumptions when comparing terms. Taxes, insurance, and other housing costs can affect the household budget, but they are separate from principal-and-interest payments.
Compare total interest across the remaining life of the current loan and the full new term, not just the first month’s payment.
Which Refinance Type Fits Your Goal?
A rate-and-term refinance suits borrowers changing their rate or payoff schedule, while a cash-out refinance adds borrowed equity to the new balance. Start with the goal, because loan structure affects the costs and terms you should compare.
Eligible FHA, VA, or USDA borrowers may have streamline refinance options with less documentation. The exact program and terms depend on the loan and borrower.
| Refinance type | Typical goal | What changes in the loan | Key consideration |
|---|---|---|---|
| Rate-and-term | Change rate or payoff schedule | Rate, term, or both | Compare total loan costs |
| Cash-out | Borrow against home equity | New loan has a larger balance | More mortgage debt |
| Streamline | Refinance some government-backed loans | Loan terms may change | Program eligibility applies |
| No-closing-cost | Reduce upfront costs | Costs shift into balance or rate | Compare APR and total cost |
Rate-and-term refinance for changing rate or term
A rate-and-term refinance replaces the current mortgage to change its interest rate, loan term, or both. It does not add cash from home equity to the balance.
Compare the new schedule with the time left on your current mortgage. A lower monthly payment can still mean a longer repayment period.
Cash-out refinance for borrowing against equity
A cash-out refinance replaces the existing loan with a larger mortgage and gives the borrower the difference in cash. The larger balance means more debt is secured by the home.
Streamline refinance for some government-backed loans
Some FHA, VA, and USDA borrowers may qualify for streamline programs with less documentation. A VA refinance quote is personalized to the borrower, loan type, equity, points, and lender.
For 15-year refinance rates, compare same-day personalized 15-year APR offers instead of treating a national average as your personal quote. For current VA refinance mortgage rates, compare equivalent offers using the same loan terms and costs.
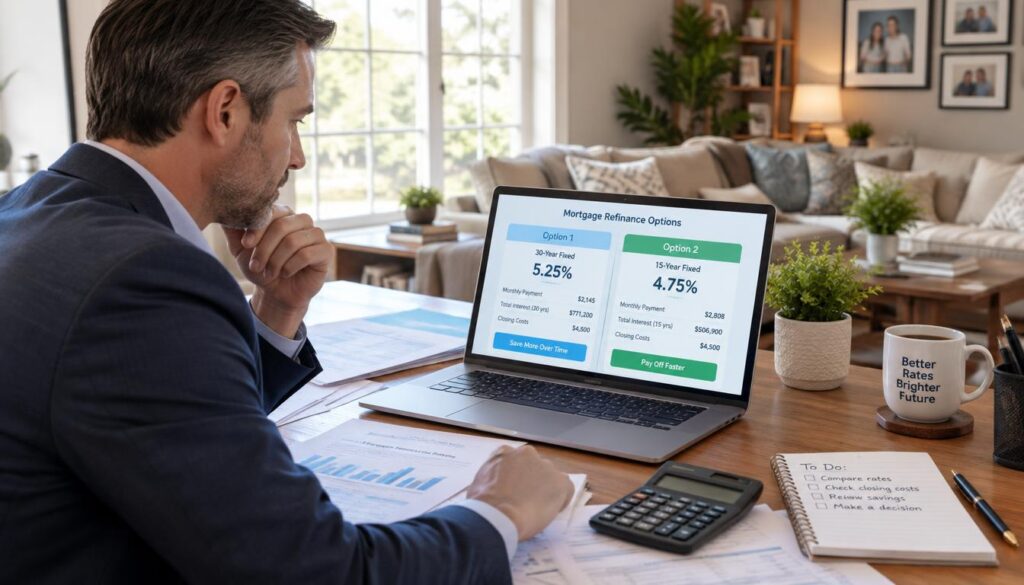
Match the refinance type to the goal before comparing the rate, APR and total borrowing cost.
What Do You Need to Qualify for a Refinance?
A credit score of at least 620 is a common refinance benchmark, but stronger credit and a manageable debt load can help borrowers qualify for better terms. These are common guides, not a promise of approval.
Lenders generally prefer a debt-to-income ratio of 43% or less. Some may consider factors such as several months of mortgage payments in reserve, and loan programs can set different rules.
Credit, income and debt
Review your credit report and make sure your income records reflect your current situation. Lenders also weigh monthly debts against income when deciding whether a new payment is manageable.
Use this checklist to prepare:
- Credit report and any errors to dispute.
- Income records.
- Monthly debt payments.
- Current mortgage balance.
- Estimated home value.
Equity and mortgage insurance
Conventional lenders generally require at least 20% home equity for the best rates and to avoid mortgage insurance. Other programs can differ, so a borrower below that level may still have options.
Mortgage insurance adds cost to some loans, so include it when comparing monthly payments. A low principal-and-interest payment may not show the full housing cost.
Check your estimated equity and mortgage-insurance implications before treating a low quoted payment as the full cost.
When Does a Cash-Out Refinance Make Sense?
A cash-out refinance may fit a defined need such as consolidating costly debt or financing a home improvement, but it increases the mortgage balance. Use the money with a purpose, not simply because equity is available.
Cash-out rates are generally higher than rate-and-term refinance rates. A rate surcharge can be substantial for borrowers with credit scores below 640, though the size depends on the offer.
Consolidating high-interest debt
Using home equity to pay high-interest debt may lower interest costs, but it changes unsecured debt into debt tied to the home. Compare the new mortgage cost with the debt payments you plan to replace.
Keep a plan for avoiding new balances on paid-off credit cards. Otherwise, a borrower could end up with both a larger mortgage and renewed credit-card debt.
Funding value-adding home improvements
A needed repair or planned improvement may support the home’s use or value. Get a clear project budget, and borrow only what the work requires.
Reasons to avoid turning equity into spending money
Vacations, everyday purchases, and items that lose value do not improve a borrower’s long-term financial position. The cash may feel separate from the mortgage, but repayment lasts much longer.
Missing payments can put the home at risk because it secures the larger loan. Compare a cash-out refinance with a HELOC and home equity loan before choosing how to borrow.
Do not put the home at risk for spending that does not improve your long-term finances.
How Does a No-Closing-Cost Refinance Work?
A no-closing-cost refinance does not make fees disappear; it shifts them into the loan balance or rate. No upfront bill does not mean no borrowing cost.
The two common tradeoffs are a larger loan balance or a higher interest rate. The lender may add fees or discount points to the loan, or price the loan at a higher rate.
Financing costs raises the amount owed and may lead to more interest over time. Taking a higher rate can also increase monthly payments and total interest.
This structure may suit a borrower who needs immediate cash-flow relief or expects to move soon. A long-term borrower may pay less by covering costs upfront, depending on the quotes.
Compare APR and total loan balance, not just the upfront amount. Compare the total amount owed and interest paid over your expected time in the home before choosing this structure.
What Can You Do Instead of Refinancing?
A HELOC or home equity loan can provide access to equity while preserving the rate on your current first mortgage. Keeping that loan intact may matter when its rate is lower than a new mortgage offer.
These options leave the existing first mortgage in place, while extra principal payments can shorten its payoff. A loan modification may adjust the rate or term for a borrower facing hardship.
| Option | Main purpose | Effect on existing first mortgage | Key tradeoff |
|---|---|---|---|
| HELOC | Borrow against equity as needed | Stays in place | Separate loan terms apply |
| Home equity loan | Borrow a set amount | Stays in place | Adds a second loan payment |
| Extra principal payments | Pay down the balance faster | Stays in place | Uses cash now |
| Loan modification | Seek payment relief during hardship | Terms may change | Lender approval is needed |
Keep the current first mortgage and borrow against equity
A HELOC is a home equity line of credit, which lets a borrower draw against available equity. A home equity loan provides a set amount, often with its own payment and terms.
Both can preserve the first mortgage’s rate, but they add another loan secured by the home. Compare the full costs and payment terms before borrowing.
Pay down principal or ask about a loan modification
Extra principal payments reduce the balance and may help pay off the mortgage sooner. Ask the lender how to mark the payment so it goes to principal.
Confirm how an extra payment is applied before sending it, so it reduces principal rather than being held for a future payment.
How Should You Compare Refinance Loan Estimates?
Request comparable Loan Estimates from at least three lenders so rate and fee differences are visible side by side. Use matching terms for each request, including loan amount, term, rate type, points, and borrower assumptions.
A lender generally must deliver a Loan Estimate within three business days after receiving a mortgage application. The form lays out key loan terms and estimated costs in a standard format.
Request comparable offers
Send each lender the same core details and ask for the same type of refinance. A quote for a different term or rate structure will not make a fair comparison.
Review each estimate for:
- Interest rate.
- APR.
- Lender fees.
- Discount points.
- Monthly principal-and-interest payment.
Compare APR, fees and loan structure
APR includes the interest rate and certain loan costs, so it can help compare offers. It does not replace checking individual fees, points, and the full loan terms.
Make sure the lender used the same loan amount and occupancy assumptions. A lower payment may result from borrowing less or choosing a longer term, rather than a lower overall cost.
Check for a prepayment penalty on your current loan, since it can reduce savings. Include any prepayment penalty in the cost comparison before accepting a new loan.
Should You Lock a Refinance Rate or Wait?
A rate lock can protect an offered rate from increases while the refinance moves toward closing. The protection is temporary, and its length and conditions depend on the lender.
Rate locks commonly last about 30-60 days. Rates can change daily or more than once during a day, so the lock period should fit the expected closing schedule.
A lock can make monthly payments easier to plan by holding the offered rate steady during the agreed period. The lock does not remove other costs or guarantee loan approval.
Consider your expected closing date, recent rate movement, and comfort with possible payment changes. No one can reliably predict the market’s next move.
Ask whether the lender charges for a lock, what conditions apply, and whether the rate can change if your loan details change. Expiration terms and fees vary by lender.
Check the lock’s expiration date against the expected closing date and ask what happens if closing is delayed.
What Should We Prepare Before Comparing Offers?
Gather your current loan balance, interest rate, remaining term, estimated home value and credit score before requesting a personalized quote. Complete details help lenders price comparable offers.
Set a clear goal and a monthly payment your household can sustain. Common goals include lowering the monthly payment, paying off the loan faster, or accessing home equity.
Gather the current loan and property details
Check your latest mortgage statement for the balance, rate, and remaining term. Use a recent estimate of your home’s value and a current credit score when comparing offers.
Keep the same figures for each lender unless a detail changes. Consistent inputs help show whether price differences come from the lender or a different loan setup.
Set the goal and payment limit
Choose the main result you want before reviewing rates. A lower monthly payment, a faster payoff, and access to equity can call for different loan structures.
Decide what payment fits your budget after accounting for other housing costs. A quote that looks appealing on paper may not fit once the household’s full expenses are considered.
Bring the same loan details and payment goal to each comparison. That makes differences between personalized offers easier to judge.
We can review personalized offers with you, without promising a rate, approval, or savings. Bring those details and your payment goal to our team to compare offers that fit the same terms.
Conclusion
A refinance is worth pursuing when its total cost, payment and loan term support the financial goal you care about most. A lower rate or payment alone does not guarantee a better outcome.
Judge each offer by the time you expect to stay in the home and the full cost of the new loan. A payment that fits today should also support your longer-term plans.
Gather your current loan details and ask our team to compare personalized options.