In 2025, U.S. investment advisers managed $176.8 trillion, yet that scale cannot make retirement advice personal. The Best Retirement Planning Services help us connect our savings to the life we want.
A retirement plan has to do more than choose investments: it has to show how your savings will support the life you want. We compare ongoing human advice, flat-fee planning and digital tools, with attention to fit, fees and trust, not promises of investment returns.
Retirement choices affect our money, work and daily life for years. A plan should account for the person behind the numbers, including health needs, family goals and comfort with investment risk.
Key Takeaways
- Choose help based on the retirement decisions you need to make.
- Compare the full fee, not just a quoted percentage.
- Check the individual advisor, service scope and written agreement.
- Use planning software for projections, not personal ongoing advice.
- A clear fee agreement and a plan tailored to your circumstances are better starting points than a famous name.
What Retirement Planning Services Actually Cover
A retirement advisor can help coordinate income, investments, taxes, healthcare and estate decisions in one plan. The best financial help links those choices to your goals, rather than treating each account as a separate problem.
A retirement plan should cover the decisions that shape both your income and your day-to-day security. A financial advisor may help us with six needs:
A good retirement plan connects income, investments and practical choices. It should reflect the household, not just the account balance.
- Retirement income and the order for withdrawals.
- Social Security timing and how benefits fit other income.
- Tax planning for accounts, withdrawals and future income.
- Investment management that matches the plan and risk level.
- Healthcare costs and insurance needs before and during retirement.
- Estate coordination for beneficiaries, documents and family goals.
The CFP Board describes a planning process that starts with a client’s circumstances and goals. Its financial planning process guide also covers recommendations, implementation and progress checks.
Employer plans and advisory services are different
Employer retirement plans are savings programs, not full advisory services. Compare a workplace plan’s employer match, investment choices, fees and vesting rules, which decide when employer contributions belong to you.
Which companies have the best retirement plans? The strongest choice for an employee is the plan with a useful match, suitable investments, fair costs and vesting rules that fit their work plans. An employer’s brand alone cannot answer that question.
Advisory services may help us manage decisions across multiple accounts and income sources. They may also review an employer plan, but their fee is separate from the plan’s investment costs.
Compare an employer plan’s match and investment costs separately from the cost of hiring an advisor.
Best Retirement Planning Services for Different Needs
For retirees who want personalized ongoing income help, Retirable is a direct fit; Facet is the flat-fee option, while Mercer Advisors and Creative Planning suit broader wealth needs. Service fit matters more than a star rating when advisors charge different fees and set different minimums.
Compare each service’s scope, account minimum and written fee before choosing a firm. The figures below show stated pricing, not a promise that every household will pay the same amount.
| Provider | Best fit | Account or investment minimum | Stated fee |
|---|---|---|---|
| Retirable | Retirement-income help | $0 | 1% of AUM, capped at $10,000 yearly |
| Facet | Flat-fee comprehensive planning | $0 to join; $500 investment minimum | $2,600-$8,700 per year |
| Mercer Advisors | Complex wealth coordination | No account minimum; $1,200 minimum fee | 0.50%-1.30% of AUM |
| Creative Planning | Comprehensive wealth management | $200,000 | 0.25%-1.20% of AUM |
| Aspiriant | Larger portfolios seeking lower AUM rates | $1.5 million | 0.20%-0.85% of AUM; $14,000 minimum yearly |
Retirable’s fee is based on assets under management (AUM), the investments a firm manages for a client. Its annual cap can matter to retirees with larger accounts, but a lower percentage does not always mean a lower bill.
A low percentage fee can still cost more than a flat fee when the portfolio is large. Facet’s set annual range may suit clients who want broad planning without tying the planning fee to portfolio size.
Mercer Advisors, Creative Planning and Aspiriant offer different approaches to wealth management and planning. A stated AUM rate may change by account size or service tier, while minimum fees can raise the effective cost.
Use the shortlist to start a conversation about service and fit, not to treat a provider label as a personal recommendation. Confirm the written fee schedule and minimum fee before scheduling a proposal review.
Other Wealth Management Firms to Compare
A fast-growing firm can be worth researching, but growth alone does not show whether its advice suits a retiree. Growth is a clue about a business, not proof of strong client outcomes or investment performance.
Revenue growth measures a company’s expansion, not the quality of advice a client receives. These firms offer starting points for research, with each describing a different mix of retirement planning and wealth management.
Growing firms are not automatically a fit
Savvy Wealth ranked No. 11 on the 2026 Inc. 5000, with about 13,086% three-year revenue growth. In 2026, it reported more than $8 billion in client AUM and more than 150 advisers.
Secure Investment Management ranked No. 48, with 5,441% growth. It describes itself as an independently owned registered investment adviser focused on conservative planning for retirees and people nearing retirement.
Peak Retirement Planning ranked No. 329, with 1,023% growth. Its five stated planning areas are tax efficiency, investments, income, healthcare and estate planning.
Abich Financial Wealth Management ranked No. 338, with 1,004.2% growth. Its services include retirement, income, tax, Social Security and wealth-preservation planning.
Match the firm’s planning scope to your needs
These growth rankings can help us find firms to investigate, but they cannot show how an advisor handles a client’s account. A high-growth wealth management firm may serve a different client type or offer a different level of access.
The best wealth management companies for one household may not suit another. Compare the actual advisor, the planning scope, account minimum and written fee agreement before deciding whether a firm fits.
Ask which advisor and specialists would serve your account, rather than relying on the firm’s growth profile.
Free and Lower-Cost Digital Planning Options
If we mainly need to test retirement scenarios, a free planning tool may be enough; automated investing is a different service because it manages a portfolio. Planning software models choices, while an investment service selects and manages investments.
A calculator can model scenarios, but it does not create a personalized, ongoing fiduciary relationship. A fiduciary is a financial professional’s duty to put a client’s interests first when providing advice.
| Tool or service | Category | Price | Feature or access detail |
|---|---|---|---|
| Empower Retirement Planner | Planning tool | Free | Monte Carlo simulations model plans, income and expenses |
| Boldin | Planning software | Free version; PlannerPlus $14 monthly, billed yearly | PlannerPlus follows a 14-day trial |
| ProjectionLab | Planning software | Basic free; Premium $129 yearly | Premium follows a 7-day trial |
| Fidelity Go | Automated investment management | No advisory fee below $25,000; 0.35% yearly at $25,000 or more | Manages investments in an account |
| SoFi Automated Investing | Automated investment management | 0.25% yearly, plus applicable fund fees | Members can access CFP professionals at no extra cost |
Planning tools for do-it-yourself projections
Empower’s Retirement Planner uses Monte Carlo simulations, which test many possible investment outcomes. Users can model more than one plan and change income or expense assumptions.
Boldin offers a free version and PlannerPlus for $14 per month when billed annually after a 14-day trial. ProjectionLab has a free Basic plan and Premium for $129 per year after a 7-day trial.
Fidelity’s free Planning & Guidance Center includes retirement-readiness, Social Security, Roth-conversion, required minimum distribution (RMD) and retirement-income calculators. These tools help us test assumptions, but they do not manage investments.
Automated investment management
Fidelity Go manages an investment portfolio, with its stated advisory fee tied to the account balance threshold. SoFi Automated Investing charges an annual advisory fee and offers members access to CFP professionals at no extra cost.
Automated management can help with portfolio choices, but it does not always include a full retirement plan. Check whether fund expenses are separate from an advisory fee before comparing digital prices.
How Retirement Advisor Fees Compare
The common pricing choices are AUM, flat annual, hourly and commission-based fees, and each changes how an advisor is paid. The fee structure affects the bill and can shape which service makes sense.
AUM fees rise with the assets under management, while a flat fee does not automatically rise as a portfolio grows. Typical costs vary by firm and service, so compare the full amount rather than one rate.
| Fee model | Typical cost | What the client pays for | Cost consideration |
|---|---|---|---|
| AUM | 0.50%-1.25% of portfolio | Ongoing investment management and advice | The bill grows as managed assets rise |
| Flat annual fee | $2,500-$10,000 per year | Planning or ongoing advice for a set fee | The fee does not automatically rise with assets |
| Hourly fee | $250-$400 per hour | Advice for a set amount of professional time | Total cost depends on hours used |
| Commission | Typically 1%-8% of product sold | A product sale or transaction | Cost can be built into the product |
Percentage-based and flat fees
An AUM fee, sometimes called an aum fee, is charged as a percentage of a managed portfolio. For example, the same rate costs more dollars as the account grows.
A flat annual fee gives the client a set planning cost, although the services included can differ. Ask whether investment management, tax planning and meeting access are part of the fee.
A higher fee can cut into investment growth over time. On a hypothetical $750,000 portfolio, a 1% higher annual fee over 25 years could cost roughly $250,000 in lost compounding, depending on returns.
Hourly advice and commissions
Hourly advice can suit a focused question or a plan review, while commissions pay a professional when a client buys a product. Those costs may not appear as a separate annual invoice.
Compare the same service across models, including fund costs and charges outside the advisor’s fee. Ask for the total annual cost, including fund expenses and any platform or planning charges.
How Fee Structure Can Create Conflicts of Interest
Ask whether the advisor receives money from anyone besides you, because the answer can change how a recommendation is paid for. Who pays can affect the advice or product a client hears about.
Fee-only means the advisor is paid by clients and receives no product commissions. Fee-based professionals may collect client fees and commissions, so the terms are not interchangeable.
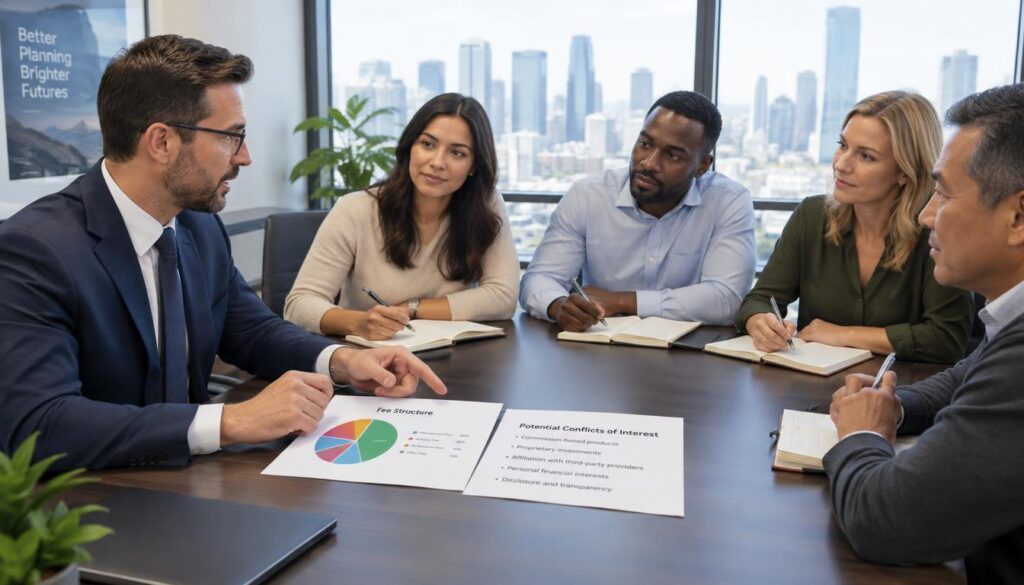
Fee-only and fee-based are not interchangeable
A commission-based professional earns money from products sold. A fee-only financial advisor earns client fees, while a fee-based advisor may earn both client fees and product commissions.
A dual-registered professional may act as a fiduciary when giving advice and as a commissioned broker when selling products. Different standards can apply to those roles, so the title alone does not explain how each recommendation is paid.
Ask who gets paid when a product is sold
Indexed universal life insurance and fixed indexed annuities can carry upfront agent commissions of 6%-10% of the premium. That does not by itself prove a product is unsuitable, but it makes payment details important.
Ask whether an advisor or another party receives a commission, referral payment or other benefit from a recommendation. Request the answer in writing and ask for every commission or referral payment connected to a recommendation.
What Financial Advisor Rankings Can and Cannot Tell You
A financial-advisor ranking can help identify firms to investigate, but it cannot tell you how the advisor assigned to you will handle your retirement plan. Rankings are filters, not personal reviews of every advisor at a firm.
There is no universal top 10 or top 100 list that proves one advisor is right for every household. Lists use different measures, and firm size does not show whether an individual advisor fits your needs.
Compare the ranking method, not just the name
In 2025, U.S. investment advisers managed $176.8 trillion, up 22.3% from $144.6 trillion. The industry had 16,544 advisers and 73.7 million clients, with the client count up 7.7%.
Non-clerical investment-adviser employment reached 1.1 million in 2025, up 7.5%. About 67.4% of advisers managed under $1 billion, and 87.3% managed under $5 billion.
Advisers focused on individual clients averaged eight employees and $424 million in AUM. Those figures show a wide mix of firm sizes, not a single model for good service.
Barron’s 2026 state rankings assessed more than 7,000 advisers using AUM, revenue, regulatory records, practice quality and philanthropy. The ranking did not measure investment performance.
Newsweek’s 2026 ranking used SEC reports from September 2025, so it is a historical view rather than a sole basis for choosing an advisor. The 2026 Inc. 5000 ranked eligible private U.S. companies by revenue growth from 2022 to 2025.
Firm size does not measure your advisor’s fit
To qualify for the Inc. 5000, a company needed revenue by March 31, 2022, at least $100,000 in 2022 revenue and at least $2 million in 2025 revenue. Those rules track business growth, not the outcome of an individual client’s plan.
The biggest financial advisory firms by AUM are not necessarily the best fit for a particular retirement household. A large firm may offer many services, while a smaller firm may provide closer access to a dedicated advisor.
Read the ranking criteria, then verify the individual advisor’s experience and record.
Which Credentials Matter for Retirement Advice
For a comprehensive retirement plan, a CFP is a useful credential to look for; specialized designations can matter when the work is narrower. Match the training to the advice you need.
Credentials show education or specialization, but they do not guarantee a good fit. We should also check an advisor’s work with retirees, communication style and disciplinary history.
Credentials for a comprehensive financial plan
The CFP Board sets certification standards and offers a search tool to find CFP professionals. Its CFP certification and search site describes education, training and ethical standards for the credential.
- CFP: broad financial planning, including retirement, tax and estate topics.
- RICP or RMA: specialized training focused on retirement income.
- CFA: investment analysis and portfolio-focused expertise.
- CPA: tax expertise, especially useful for complex tax questions.
Credentials for specialized retirement questions
A retirement income credential may help when the key issue is how to draw money across accounts over time. CFA training may matter more when we need detailed investment analysis.
A CPA can help with complex tax questions, while a CFP may connect tax choices to the wider plan. A credential does not replace experience with people facing similar retirement decisions.
Ask how the person’s credential connects to the specific work you want done.
Financial Advisor Red Flags to Watch For
A promise of guaranteed returns is a serious warning sign because no advisor can remove investment risk. Guaranteed returns deserve special caution when the person cannot explain the terms and risks.
Pause if an advisor pressures you to buy quickly or hides the full cost. A poor process is a warning sign even when the firm appears on a ranking.
- Vague or undisclosed fees that leave the total cost unclear.
- Pressure to buy a product before you have time to compare it.
- Promises of guaranteed returns without a clear, limited guarantee.
- Advice that ignores your income, goals, risk level or family needs.
- Evasiveness about communication or disciplinary history.
Product commissions can give an advisor an incentive to sell a product, so ask how a recommendation is paid for. Unclear answers make it harder to judge whether the advice serves your needs.
There is no named company that should be called the worst based on a general ranking. Judge the conduct and disclosures of the specific advisor you meet.
Pause the process if the advisor cannot explain the recommendation, its risks and its full cost.
What a Useful Retirement Plan Should Include
A useful retirement plan shows how we may turn savings into income over time, not just how the portfolio is invested. Income planning helps connect spending needs with account choices and taxes.
The 4% rule starts with a 4% first-year withdrawal, then adjusts later dollar withdrawals for inflation. It was designed around a 30-year retirement, so it is a planning assumption, not a promise.
Model income, withdrawals and taxes
With a hypothetical $1 million portfolio, the first-year withdrawal would be $40,000. At 2.5% inflation, the second-year withdrawal would be $41,000.
The example assumes a portfolio split evenly between stocks and bonds. It excludes taxes and investment fees, which can reduce what a retiree keeps.
A written retirement plan can project income through age 95 and test how choices affect the household. The CFP Board’s financial planning process guide outlines how professionals can analyze options, make recommendations and monitor progress.
Plan for healthcare, estate needs and surprises
A useful plan should cover the following details:
- Income projections through age 95 and Social Security timing.
- Tax strategy, withdrawal sequencing and required minimum distributions.
- Healthcare costs before Medicare eligibility at age 65.
- Estate coordination with beneficiaries and other planning documents.
- Monte Carlo stress testing across many possible investment outcomes.
Tax planning can change which account we draw from first, while healthcare costs can shift spending needs before Medicare begins. Estate coordination can also keep account instructions aligned with family goals.
Treat a withdrawal rule as a planning assumption to test against your own timeline, taxes and spending needs.
2026 Retirement Account Contribution Limits
In 2026, the employee contribution limit for a 401(k), 403(b), governmental 457 plan or TSP is $24,500 before eligible catch-up contributions. Catch-up rules raise that amount for eligible savers.
The general defined-contribution limit is separate from employee deferrals and catch-ups. Annual additions usually cannot exceed the lesser of 100% of compensation or the applicable dollar limit.
| Account or limit | 2026 amount | Who or what it applies to | Key condition |
|---|---|---|---|
| 401(k), 403(b), governmental 457 or TSP deferrals | $24,500 | Employee contributions | Before eligible catch-ups |
| Age-based catch-up | $8,000; $11,250 for ages 60-63 | Eligible employees age 50 or older | Age 50+ total can reach $32,500 |
| IRA | $7,500; $1,100 age-50 catch-up | Individual retirement accounts | Catch-up applies at age 50 or older |
| Defined-contribution annual additions | $72,000; $80,000 with catch-ups; $83,250 for ages 60-63 | Overall plan additions | General limit excludes catch-ups; also capped at 100% of compensation |
For eligible employees age 50 or older, the regular $8,000 catch-up can bring deferrals to $32,500. Employees ages 60 through 63 may use the higher $11,250 catch-up.
The general $72,000 annual-additions limit excludes catch-up contributions. With catch-ups, the limit is $80,000, or $83,250 for people ages 60 through 63.
Confirm plan eligibility and how employer contributions affect the annual additions calculation.
Questions to Ask Before Hiring an Advisor
Ask the advisor to explain how they would handle your first five years of retirement withdrawals before you sign an agreement. Specific answers can show whether the person understands your needs.
Ask about duties, all forms of pay, total cost, experience and day-to-day service. Clear answers matter more than a polished presentation.
Ask about duties, compensation and experience
- Are you a fiduciary for every service you provide, and will you confirm that in writing?
- How are you paid, including any third-party payments?
- What is my all-in annual cost?
- How many retiree households do you personally serve, and who is on my team?
- How will you approach my withdrawal order, tax strategy and communication schedule?
Ask how the plan works in real life
Ask for a sample anonymized plan to see how the advisor presents decisions and next steps. Find out who covers the relationship when the advisor is away.
Ask how often the team reviews a plan and what changes would prompt another meeting. A yearly relationship review is a useful baseline, with extra meetings when your circumstances or needs call for them.
A dedicated advisor may handle the main relationship, while other team members help with tax or investment work. We should know who answers routine questions and who makes final recommendations.
Compare the clarity of the answers, not just the confidence of the presentation.
Is a Retirement Planner Worth the Cost?
A retirement planner is most useful when coordinated decisions about income, taxes and investments are hard to manage alone. Personal advice can help when one choice affects several parts of the plan.
Complex accounts, tax-sensitive withdrawals, estate questions and healthcare choices can make professional planning valuable. A person with predictable pension income and confidence managing investments may need less help.
A financial advisor can coordinate Social Security, Medicare, tax choices and investment withdrawals. That work may be useful when income comes from several accounts or healthcare decisions affect retirement timing.
Simple finances do not always call for ongoing wealth management. Someone with a reliable pension, few accounts and a clear investment plan may be able to manage without a continuing advisory relationship.
Hiring an advisor does not require handing over the whole portfolio. A one-time plan review or advice-only engagement can answer a defined question without ongoing investment management.
Pay for the specific help you need, rather than assuming ongoing investment management is the only option.
How to Verify an Advisor and Build a Shortlist
Check the individual professional’s registration and record before deciding whether a firm belongs on your shortlist. Start with the person, then assess the firm’s services and access.
Verify registration and disciplinary records before you rely on a firm’s name or marketing. A local firm’s small size does not automatically mean poor advice, and a national brand does not guarantee a suitable advisor.
Check the individual advisor’s record, service scope and written costs before you commit. A well-known firm name cannot replace those checks.
- Define the planning problem you want help solving.
- Find candidates through NAPFA, the CFP Board or XY Planning Network.
- Check records through FINRA BrokerCheck and the SEC’s Investment Adviser Public Disclosure database.
- Compare service scope, account minimums and written fees.
- Meet the actual advisor and ask who will handle your account.
These directories can help us find planners, while BrokerCheck and SEC IAPD offer ways to review a professional’s record. Confirm that the person you meet is the person who will provide the advice.
Compare local providers’ services, minimums and meeting access before booking. Some firms offer local office meetings, while others rely on phone or video contact.
Schedule conversations with three candidates and choose the one who answers directly, documents the costs and understands your needs.
Conclusion
Trust in a retirement-planning relationship comes from clear advice, clear fees and a process you can understand. The best fit is the service that addresses our actual retirement questions with transparent costs and an accountable advisor.
We do not need the biggest firm or the most complex plan. We need advice that matches our goals and a working relationship where we know who is responsible.
Write down your three biggest retirement questions and bring them to your first advisor meeting.