A large purchase can look like an obvious growth move until we ask whether its future benefits justify tying up money today. We might expand capacity to meet demand, or preserve funds for another opportunity. The choice can shape long-term growth and limit what the business can fund next.
Capital Budgeting Decision Analysis gives us a disciplined way to test projected cash flows and strategic fit before we commit. Incremental cash flow is the change in a company’s cash receipts and payments caused by taking a project. We can use that measure to focus on what the investment actually changes, not just its accounting totals.
Returns remain uncertain, even when a proposal looks strong on paper. A clear review helps us weigh the likely benefits against the money, time, and options we give up. A sound decision starts by testing the project’s assumptions rather than trusting its pitch.
Key Takeaways
- Compare expected cash effects with strategic goals.
- Use consistent assumptions to assess competing projects.
- Choose a discount rate that reflects project risk.
- Test how uncertain inputs could change project value.
- Review actual results against the approved forecast.
What Is Capital Budgeting Decision Analysis?
Capital budgeting is the structured evaluation of major investments whose benefits are expected to extend beyond the current operating cycle. It helps a business decide which long-term projects can increase cash flow or advance strategic objectives. Limited funds make that choice important: approving one proposal can leave less money for another.
Capital expenditures create benefits for more than one year, while operational budgets cover day-to-day expenses. A disciplined review helps management spot proposals that could create or destroy value and align funding with strategic goals. It supports management judgment; it does not replace it.
Before committing funds, we should be able to explain how a proposal serves both the organization’s strategy and its financial needs.
The difference between capital and operating budgets is clearest across three areas:
- Time horizon: capital budgets cover long-term assets; operating budgets cover the current period.
- Typical spending: capital budgets fund equipment or facilities; operating budgets fund routine supplies and payroll.
- Purpose: capital budgets support lasting capacity or strategic aims; operating budgets keep daily work running.
These choices also connect to broader financial strategy and growth plans, since funding must serve more than one business goal. A proposal should show how its expected benefits fit the organization’s needs, not just why its sponsor wants it.
Capital budgeting decisions can be hard to reverse once a company has bought an asset or built a site. A useful proposal names the goal, the expected financial effect, and the reason the organization should act now. Before committing funds, we should be able to explain how a proposal serves both the organization’s strategy and its financial needs.
Which Investments Belong in a Capital Budget?
Replacing worn equipment, adding production capacity, and meeting a safety requirement can all belong in a capital budget, even when their reasons differ. These long-lived commitments can shape future cash flows and business choices. Their purpose helps determine how we judge them.
Expansion forecasts are usually less certain than replacement decisions because demand and supply can change. A required compliance or safety project may still need funding when it cannot produce positive cash flows. Common categories include:
- Replacement: renew machinery or vehicles that no longer meet operating needs.
- Expansion: add production capacity or enlarge a warehouse.
- New products or services: fund development, testing, and launch needs.
- Regulatory, safety, or environmental work: meet rules or reduce harm and risk.
- Special projects: consider research and development or large-scale employee training.
Examples include an ERP system, a production facility, company vehicles, and a warehouse expansion. A business may also fund research and development or extensive training when the work supports a long-term need. Different reasons call for different tests, so a safety mandate should not be judged only by its direct cash return.
For an expansion, sales forecasts depend on future market demand and the supply available to serve it. A replacement decision often rests on the known cost and performance of an existing asset. Classify a proposal by its scale, duration, and strategic or required purpose before choosing how to evaluate it.
What Are the Five Stages of the Investment Decision Process?
A consistent process moves a proposal through five stages, so projects face the same basic decision discipline. The stages are strategic alignment, information gathering, forecasting value, decision-making, and implementation and evaluation. Each creates a record that helps management explain its choices.
Use the same core steps for every proposal, then make room for relevant strategic factors. A shared process helps teams compare projects without treating a polished pitch as proof. It also makes later reviews more useful.
Align the proposal with strategy and gather information
First, check whether the proposal supports the organization’s goals and fits its plans. A project that does not serve a clear need may not deserve further work. This strategic alignment stage sets the question the analysis must answer.
Next, gather information about the proposed asset, expected use, costs, and likely benefits. Teams should ask what alternatives exist and what the project changes for the business. This information-gathering stage builds the facts for the forecast.
Forecast the project’s value
Third, forecast the project’s value using the information collected. Management can apply appraisal methods to estimate whether the expected cash effects justify the commitment. Forecasts should use clear assumptions so reviewers can see how the result was reached.
Financial analysis does not capture every factor. A proposal may support a long-range strategic goal that matters beyond its near-term cash return. A strategically important project may deserve qualitative review even when financial metrics are not the only deciding factor. That judgment should be clear and tied to the organization’s goals.
Decide, implement, and evaluate
Fourth, decision-makers weigh the financial results alongside strategic importance, project risk, and the organization’s other needs. They decide whether to approve, reject, or revise the proposal. A clear decision record explains why the project won support.
Fifth, implement the approved project and evaluate its performance. Compare actual cash flows with the forecast, then examine favorable and unfavorable gaps. A budget may miss because sales came in lower, costs rose, or work took longer than expected.
Good records make that review fair. They show which assumptions drove the approval and whether the approved scope changed during implementation. Record the assumptions behind the approval so that later reviews can compare the same expectations with actual performance.
How Do We Build Credible Cash-Flow Forecasts?
A useful forecast includes only cash flows that change because we accept the project. That difference matters: broad accounting totals can include costs the project will not cause. Forecast the cash effect of choosing the investment over rejecting it.
Do not count allocated overhead as an incremental cash cost unless the project changes that cost. Build the forecast from these five areas:
- Incremental revenues or savings the project is expected to create.
- Operating and implementation costs caused by the project.
- Timing and duration of cash receipts and payments.
- Salvage value expected when the asset is sold or retired.
- Depreciation and tax effects that affect after-tax cash flows.
Working capital can change as the project grows. More inventory or unpaid customer bills may tie up cash during operation, and those needs can reverse at the project’s end. Include the timing of those changes rather than treating them as a permanent cost.
Depreciation is not a cash payment, but it can lower taxable income and change tax payments. When we calculate project cash flow, we add depreciation back after accounting for its tax effect. Keep the cash timing clear so a tax benefit does not look like cash received from a customer.
Existing overhead belongs in the model only if accepting the project changes the company’s payments. For example, a cost allocation does not create a new cash outflow by itself. Test every line in the model by asking whether that cash receipt or payment would change if the project were rejected.
Which Capital Budgeting Methods Answer Different Questions?
Use NPV to judge dollar value creation, then use the other measures to understand return rate, recovery speed, or value per dollar. Each method answers a different question, so no single figure captures every part of a project. The right reading depends on the decision at hand.
NPV below $0 is unfavorable under the NPV rule, while NPV at or above $0 is favorable. Pair it with other measures to see the forecast from more than one angle.
Discounted cash-flow methods measure value and return
Net present value (NPV) discounts future cash flows to account for time and the required return. It measures value created or destroyed after the upfront investment, future cash flows, and opportunity costs are considered. A positive result means discounted benefits exceed the costs under the chosen rate.
Internal rate of return (IRR) is the discount rate that makes a project’s NPV equal zero. A project is favorable under this test when its IRR exceeds the appropriate discount rate. IRR gives a percentage, while NPV gives a dollar value.
Consider a hypothetical software implementation with an initial cost of $200,000. It generates $60,000 each year for five years, with a 10% discount rate. The projected schedule is:
- At approval: pay $200,000.
- Year 1: receive $60,000.
- Year 2: receive $60,000.
- Years 3-5: receive $60,000 each year.
That example has an NPV of approximately $27,500 and a simple payback period of 3.33 years. The result depends on the stated cash flows and discount rate, not on a promise that software will deliver the same return in every business.
Payback methods measure recovery time
Standard payback estimates how long cash receipts take to recover the initial investment, without discounting those receipts. Discounted payback uses discounted cash flows instead, so it accounts for the time value of money during recovery.
Both payback methods ignore cash flows that arrive after recovery. Standard payback also ignores the time value of money; discounted payback fixes only that first limitation. A project can recover its cost quickly yet produce little value afterward.
The profitability index and accounting return add context
The profitability index (PI) divides the present value of future cash flows by the initial investment. A PI above 1.0 means the present value of those future cash flows exceeds the initial investment. It can help compare value per dollar when funds are tight.
Accounting rate of return (ARR) uses average accounting profit divided by the initial investment. It can provide an accounting view, but it does not account for the time value of money or cash flows. Treat a short payback as a screening signal, not proof that a project creates the most value.
When Should NPV Outweigh IRR?
If both measures agree on an independent project with conventional cash flows, the accept-or-reject decision is straightforward. Conventional cash flows have one sign change, such as an initial outflow followed by inflows. Conflicts need more care when proposals compete or cash flows change direction more than once.
NPV generally guides choices between mutually exclusive projects because it measures absolute value created. IRR rankings can differ when project scale or cash-flow timing differs.
| Case | NPV signal | IRR caution |
|---|---|---|
| Independent projects with conventional cash flows | Accept each project that meets the NPV rule | Usually gives the same accept-or-reject result |
| Mutually exclusive projects of different sizes | Compare dollar value at the suitable rate | A smaller project can show a higher percentage |
| Irregular or non-conventional cash flows | Discount the full cash-flow pattern | More than one IRR may exist |
Project relationships matter. Independent projects can each be accepted if they meet the organization’s rules. Mutually exclusive projects compete for one choice, while complementary projects may work better together. Substitute projects meet similar needs in different ways.
Non-conventional cash flows have more than one sign change, such as later costs after early receipts. They can produce multiple IRRs, making a percentage ranking hard to interpret. When mutually exclusive choices produce conflicting rankings, compare their dollar value at the appropriate discount rate before choosing.
How Should We Set the Discount Rate?
Start with WACC for a project that resembles the organization’s existing investments, then adjust for project-specific risk. Weighted average cost of capital, or WACC, is the usual starting point for the discount rate. The rate should reflect both financing costs and the risk of the investment.
A rate that is too low can make a weak project look attractive; one that is too high can reject a worthwhile project. Use a risk check before applying the rate to project cash flows.
| Project risk | Discount-rate treatment | Decision check |
|---|---|---|
| Similar to existing portfolio | Start with WACC | Under the IRR test, below WACC means no-go |
| Higher risk | Raise the rate to reflect added risk | Check that the higher hurdle fits the exposure |
| Lower risk | Lower the rate to reflect less risk | Check that the lower rate does not overstate value |
The rate should fit the project, not just the company name on the proposal. A project with different risk from the existing portfolio may need a different hurdle. Financing costs should not also be deducted in project cash flows if the discount rate already reflects them.
Rate choices affect how future cash flows compare with the initial investment. Document why the chosen rate fits the project’s risk instead of applying one company-wide figure without review.
How Can We Rank Projects When Capital Is Limited?
When available funds cannot cover every proposal, rank choices as a portfolio rather than approving projects one at a time. Funding limits change the choice: a set of projects may fit the budget better than the top single proposal. Compare both the money created and the budget each option uses.
PI can help rank value per dollar, while NPV shows the absolute value created. PI above 1.0 means the present value of future cash flows exceeds the initial investment, but PI does not account for project size.
| Situation | Useful comparison | What to watch |
|---|---|---|
| All positive-NPV proposals fit the budget | Review each NPV and strategic fit | Do not overlook project dependencies |
| Budget is constrained | Use PI to compare value per dollar | PI may make larger projects look less attractive |
| Mandatory compliance or safety project | Assess required funding and alternatives | It may need funding without positive cash flows |
A ranking by PI alone can favor smaller projects even when a larger one creates more total value. The measure helps compare use of limited capital, but it cannot replace strategic judgment or the need to meet a safety or compliance requirement.
We should check how selected projects work together and whether they fit the available funding. A mix of proposals may serve the organization better than a strict one-to-one ranking. Check that the final portfolio fits both the funding limit and the organization’s strategic priorities.
How Do We Test Uncertainty in Project Forecasts?
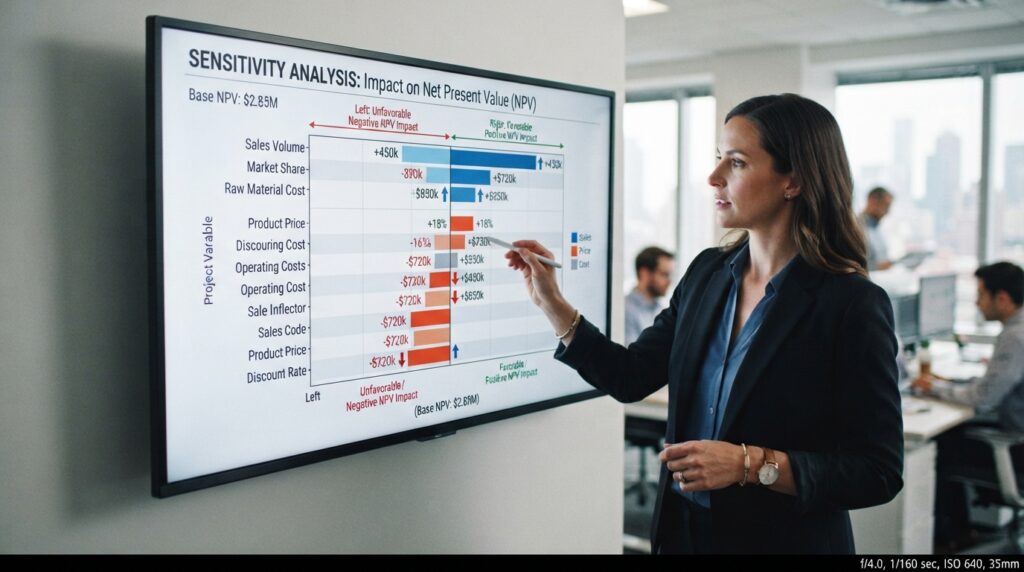
A base-case NPV is only one outcome, so we should test how it changes when the assumptions change. Sensitivity analysis changes one input at a time while holding other assumptions steady. Scenario analysis changes several related inputs together to model a coherent possible future.
The assumptions with the largest effect on NPV deserve the strongest checks before approval. A tornado diagram ranks inputs by the size of their effect; its widest bar shows the largest swing across the tested range.
Sensitivity analysis isolates one assumption
In a hypothetical case, base-case NPV is $2.0 million. A 20% change in unit sales moves NPV from $0.8 million to $3.2 million. That range shows how strongly sales volume can affect the result.
A 20% change in selling price moves NPV from $0.95 million to $3.05 million in the same illustration. The sales change creates a wider swing than the price change, so the forecast needs closer evidence on unit demand. A tornado diagram’s widest bar makes that difference easy to spot.
Scenario analysis combines related assumptions
Scenarios can pair lower demand with reduced production, or stronger sales with added staffing needs. The inputs should fit together rather than shift in ways that could not happen at the same time. A worst-case scenario is credible when its assumptions are internally consistent, not when every input is simply set to its least favorable value.
We can calculate expected NPV by multiplying each scenario’s probability by its NPV, then adding the results. The probabilities must sum to 1. Sensitivity analysis can flag assumptions for more research before the organization commits funds.
Turn the results into better research priorities
Variance across scenario NPVs can describe risk, and the square root of that variance is the standard deviation of NPV. A wider spread signals that outcomes differ more across the tested scenarios. This measure can help compare uncertainty across proposals.
Test the inputs that can change the decision, not just those that are easy to estimate. If small changes in sales or price could turn positive NPV negative, those assumptions need strong support. Prioritize research on the assumptions that can most quickly turn a positive NPV into a negative one.
How Should We Monitor and Audit Approved Investments?
An approved project still needs a disciplined check of what it actually costs and delivers. Compare actual cash flows with projections, then review favorable and unfavorable gaps rather than treating the approval as the end of analysis.
Judge performance against the approved scope and assumptions, not a revised target that erases earlier misses. A post-audit creates learning for future proposals, not just a chance to assign blame.
- Compare actual cash flows with projected cash flows.
- Track cost and schedule variances against the approved plan.
- Find the reasons for favorable or unfavorable gaps.
- Look for recurring forecast errors across projects.
A post-audit can show that teams repeatedly underestimate costs or expect benefits too soon. Those patterns can improve later forecasts if managers record the reasons behind each gap. A fair review also notes whether the project’s scope changed, without rewriting the original target.
Keep the approved forecast beside the actual results so the comparison stays clear. Record the reason for each major variance so the next forecast can correct a recurring bias.
Which Decision Errors Can Distort an Investment Case?
A polished model can still give a poor recommendation when its assumptions favor the proposal. Sponsor optimism may inflate benefits or make costs seem smaller than they are. Unsupported confidence is not a substitute for evidence.
Check whether the forecast reflects costs and benefits the project will truly change. A careful review should test the proposal’s assumptions before relying on its return measure.
Overstated benefits and understated costs
A project sponsor may focus on hoped-for sales, savings, or productivity while giving less attention to delays and added costs. Ask what supports each benefit estimate and which costs the forecast includes. Unsupported gains can make a weak investment look sound.
Sunk costs and accounting measures
Sunk costs are amounts that will not change if the organization accepts the project. They should not shape the choice between taking the project and rejecting it. Future relevant costs matter because they can still change.
ARR divides average profit by the initial investment, but it ignores the time value of money and cash flows. Use it as a supplementary accounting view, not a substitute for cash-flow analysis. A previously spent amount should not justify continuing when the project’s remaining expected value is poor.
Reassess the remaining costs and benefits as they stand today, not the money already spent.
Conclusion
We make stronger long-term decisions when the numbers and the strategic case are tested together. Credible cash-flow estimates show what a proposal may change, while an appropriate risk-adjusted discount rate helps us judge those future effects.
Strategic judgment still matters, especially when a project serves a required or long-range need. It should sit beside the financial case, with assumptions clear enough to review later.
Select an upcoming proposal and ask its sponsor to document incremental cash flows, key uncertainties, and the measures the team will review. For your next proposal, ask for a documented forecast and a clear plan to compare actual results with it.