A business can be profitable on paper and still struggle to pay its bills on time. Customers may pay slowly, growth can tie up working capital, and debt principal or asset purchases can take cash out of the business. These timing gaps can put small businesses under pressure even when sales look strong.
Cash Flow Forecasting Models help us see those gaps before they become emergencies. We can use a forecast to make better choices about spending, hiring, borrowing, and reserves. A clear view of expected cash also helps us explain upcoming needs to business partners and lenders.
We do not need a complex model to begin. We need reliable records, clear assumptions, and a plan to compare expected results with actual cash. Then we can update the forecast as customer payments, costs, and plans change. A useful forecast gives us time to make a decision before a cash gap becomes urgent.
Key Takeaways
- Cash timing can differ from reported profit.
- Match forecast detail to the decision and time period.
- Use dated receipts and payments for near-term planning.
- Reconcile starting cash before adding assumptions.
- Compare expected results with actual results often.
What Can a Cash Flow Forecast Tell Us?
A cash flow forecast estimates when money will enter and leave the business so we can judge whether cash will be available when bills are due. Liquidity is the ability to pay current obligations with cash available when they come due. A forecast estimates cash receipts and payments, then predicts the closing cash balance.
The forecast helps us spot a cash squeeze before a due date passes. Revenue can count as income before a customer pays, and expenses can appear in the books before we pay them. Profit measures business performance, while cash timing shows whether we can meet obligations on time.
Uneven cash flow troubled 50% of U.S. small businesses in a March 2026 Federal Reserve report. Inflation troubled 73%, while paying operating expenses troubled 54%. These pressures can overlap, especially when a company grows or customers take longer to pay.
Use the forecast to make spending, funding, and reserve decisions before payment dates arrive.
A forecast can help us decide whether to delay a purchase, seek funding, or keep more cash available. It also gives managers a shared view of expected cash needs. Treat a positive profit figure as no substitute for checking the timing of cash collections and payments.
Which Forecast Horizon Fits the Decision?
A forecast for next week needs finer timing than a forecast used to plan next year’s expansion. Daily or weekly views help us manage near-term liquidity, while monthly or annual views support longer-range planning. Use the shortest time buckets that help us act on a real decision.
Short-term forecasts commonly cover 1-4 weeks. Medium-term forecasts often cover 1-6 months, while long-term forecasts cover 12 months or more. A weekly view can support payroll and supplier decisions; a monthly view can help us plan a quarter or review a year.
A mixed-period forecast keeps close detail near today and a wider view farther out. For example, we can use daily buckets for the first two weeks, then weekly buckets for the following four weeks. This helps us see an immediate payment crunch without building a daily grid for the whole year.
Daily and Weekly Views for Near-Term Liquidity
Daily time buckets can show whether a large payment lands before a customer deposit. Weekly buckets suit a 13-week cash flow forecast and help us review near-term plans. Short-term views often track 30, 60, and 90 days, with expected dates rather than broad averages.
For help managing cash timing between customer receipts and bills, we can use these working capital strategies for small businesses. They pair well with a forecast that shows which week may need attention. A rolling forecast keeps a set number of periods ahead as we add actual data.
Monthly Buckets for Longer-Range Planning
Rolling monthly forecasts can keep 12 or 18 months in view as each month of actual data arrives. Annual or quarterly buckets may fit a five-year plan, such as a new location or major expansion. Short-term ranges can also include 30, 60, and 90 days; longer views may mark 180, 270, and 365 days.
- Daily buckets for immediate payment timing.
- Weekly buckets for a 13-week view.
- Monthly buckets for a one-year view.
- Annual or quarterly buckets for a five-year view.
Very fine buckets can create false precision in a long-range forecast. Broad buckets can hide a near-term cash risk. Choose buckets that reveal the timing risk you need to act on, not the most detailed grid you can build.
How Do Direct and Indirect Cash Flow Forecasting Models Differ?
Direct forecasting is the better fit when we need a detailed view of near-term receipts and payments, while indirect forecasting suits longer-range planning from projected financial statements. Direct cash forecasting uses expected cash by date. Indirect cash forecasting starts with projected income and balance sheets.
The direct approach lists customer collections, payroll, supplier payments, and other expected cash movements in each time bucket. It can roll each period’s net cash flow into the next opening balance. The indirect approach adjusts projected net income for balance-sheet changes, which can suit a longer planning period.
Under U.S. GAAP, either method can present operating cash flows, and both produce the same net cash from operating activities. GAAP encourages direct presentation, though most reporting entities use the indirect method. Direct presentation shows gross receipts and payments; indirect presentation reconciles net income to operating cash flow.
| Approach | Starting point | Typical use | What it presents |
|---|---|---|---|
| Direct forecast | Dated receipts and payments | Short-term cash management | Expected cash by time bucket |
| Indirect forecast | Projected net income and balance-sheet changes | Long-term planning | Estimated cash from financial statements |
| U.S. GAAP statement presentation | Direct or indirect operating cash flow | Financial reporting | Same net operating cash flow |
Investing and financing activities appear the same way under both U.S. GAAP methods. The difference applies to the presentation of operating activities, not the total operating cash flow. Choose the approach based on the decision and keep statement-presentation rules distinct from forecast design.
What Belongs in a Business Cash Flow Forecast?
Start each forecast period with the cash actually available, then list the cash expected to arrive and leave. Core lines include the opening balance, receipts, payments, net movement, and closing balance. Keep every material cash movement in the forecast, even when it happens only once.
U.S. GAAP groups cash flows into operating, investing, and financing activities. Operating cash flow includes day-to-day items such as customer receipts, payroll, rent, and supplier payments. These outflows can differ from the expenses recorded for the same period.
Investing activity includes equipment purchases and acquisitions as outflows, plus asset or business disposals as inflows. Financing activity includes debt or equity proceeds, loan repayments, share repurchases, and dividends. These lines help us see whether cash changes came from operations, assets, or funding.
- Opening balance: cash available at the start.
- Receipts and payments: expected inflows and outflows.
- Net movement: receipts less payments.
- Closing balance: cash left at period end.
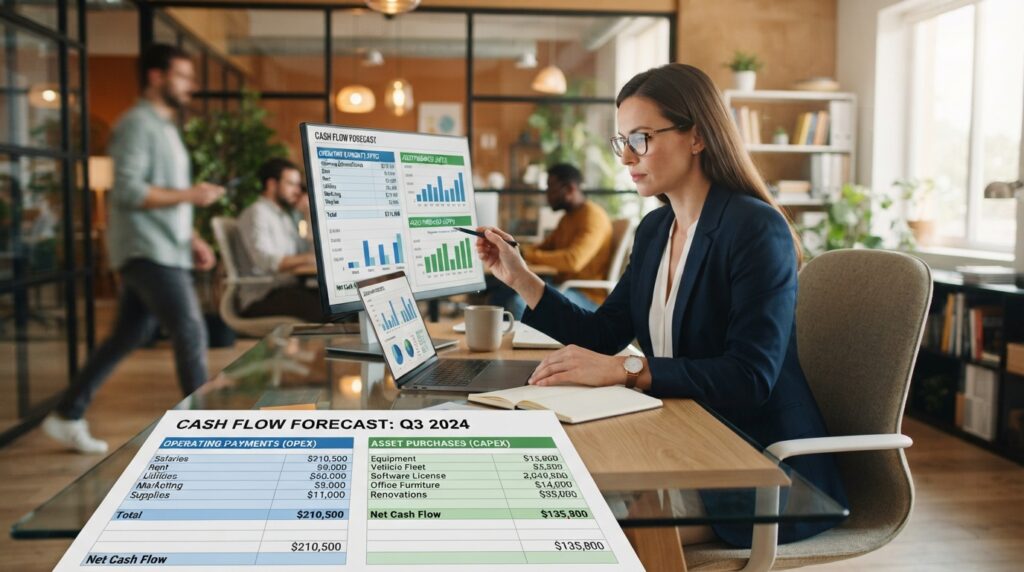
Keep one-off asset purchases and financing transactions visible rather than burying them in routine operating expenses. This makes the cash impact of a large equipment order or loan payment easier to review.
How Should We Prepare the Data and Assumptions?
The opening cash balance is only useful if it agrees with reconciled bank records. Trusted records give us a firm starting point, while clear assumptions explain what may change. Keep inputs, calculations, and outputs separate so each number has a clear role.
Gather current balances and schedules before we estimate future cash. Accounting can validate cash, accounts receivable, and accounts payable records. FP&A, or financial planning and analysis, can add business plans, growth estimates, hiring needs, pricing, seasonality, and scenarios.
- Bank balances and completed reconciliations.
- ERP or general-ledger records.
- Accounts receivable and payable aging reports.
- Payroll, tax, and debt schedules.
Reconcile the Starting Cash and Source Records
Use the latest bank reconciliation to confirm cash held across business accounts. Check the general ledger for items that have not cleared the bank. AR and AP aging reports show which customer invoices and supplier bills remain open.
Payroll, tax, and debt schedules add dated obligations that can be easy to miss in a monthly expense total. Accounting should confirm that the records reflect the current position. That check keeps an old balance from distorting the entire forecast.
Build Assumptions From Operating Drivers
Future cash depends on customer payment timing, revenue, pricing, sales volume, and seasonality. Monthly revenue drivers can include average revenue per user, average order value, average selling price, and items per order. These measures help explain why sales estimates may rise or fall.
Enter each assumption once, document its input source, and keep it apart from formulas and results. For example, a sales-volume assumption should not be hard-coded into several calculation cells. Label every assumption with its owner and source so an unexpected variance can be traced back to the right input.
How Do We Build a Cash Flow Forecast Step by Step?
Begin with the decision the forecast needs to support, then set a horizon and time buckets that fit it. A focused objective keeps the model useful, whether we need to cover payroll, plan a purchase, or review next year. Build the forecast around dated cash, not income alone.
Start by choosing the period and the question we need to answer. Then estimate the amount and timing of customer collections, new sales, financing, and payments. Last, sort those values into time buckets and replace estimates with actual results as the period closes.
- Choose the objective, forecast period, and time buckets.
- Project cash amounts and their expected dates.
- Organize the values, then update with actuals.
Forecast the Expected Receipts and Payments
For customer collections, use invoice due dates and the customer’s payment history. An AR aging report can make the estimate more realistic because an overdue invoice may not arrive next month. Collection estimates should reflect how old each invoice is, not just its face value.
As an illustration, current invoices may have 80-90% collection probabilities. Invoices 31-60 days old may have 50-70% probabilities; 61-90-day invoices may have 30-50%. Invoices over 90 days may have 10-30% probabilities.
Applying midpoint probabilities to $200,000 in receivables projects $131,000 collected next month. We can then estimate new sales, financing proceeds, payroll, rent, suppliers, taxes, and debt payments. Assign each amount to the expected payment date, rather than spreading it evenly across the month.
Lay Out a Simple Excel Projection Template
A simple cash flow forecast template in Excel should include opening cash, dated inflows and outflows, time buckets, and a closing balance. Cash flow forecasting models in Excel can start with customizable categories and formulas. The sheet should make expected cash easy to change without rewriting its calculations.
Readers looking for a free download should check the file’s access and use terms. A template can look complete while leaving out an important line or using formulas that do not fit our business. We can test a copy with a few known transactions before relying on it.
Extend the Projection Across 12 Months
A 12-month cash flow projection template in Excel can use monthly columns with separate expected and actual values. Monthly buckets let us compare each estimate with what happened, while the full year shows seasonal patterns. Keep assumptions clear so a change in price or sales volume updates the right month.
Our process should capture large, dated items as well as routine bills. A planned equipment deposit, annual insurance bill, or debt payment can affect cash more than a small recurring cost. Update the model with actuals, then roll the remaining months forward.
Keep collections tied to expected payment dates rather than treating booked revenue as cash already received.
Which Formula Calculates the Closing Cash Balance?
Calculate each period’s net cash movement by subtracting expected payments from expected receipts. The basic formula is net cash movement = inflows – outflows. Closing cash balance = opening cash balance + expected inflows – expected outflows.
Each closing balance becomes the next period’s opening balance. For working capital, monthly accounts receivable = receivable days / 30 x sales. Monthly accounts payable = payable days / 30 x cost of sales, and inventory = inventory days / 30 x cost of sales.
An indirect operating cash flow estimate can start with net income, add back noncash costs such as depreciation, then adjust for changes in operating assets and liabilities. Free cash flow to the firm, or FCFF, equals EBIT x (1 – tax rate) + depreciation and amortization – net capital expenditures – increases in net working capital. Add decreases in working capital instead.
Free cash flow to equity, or FCFE, equals cash flow from operations – capital expenditures + net debt issued. These measures answer different questions: FCFF looks at cash available to debt and equity holders, while FCFE focuses on equity holders. Check that each period’s closing balance carries forward exactly as the next period’s opening balance.
How Can We Compare a Forecast With Actual Results?
Comparing the same line items in expected and actual columns makes a forecast’s misses visible instead of hiding them in a single ending balance. A line-by-line review shows where receipts or payments differed. Record the reason for a material variance before changing an assumption.
The simplified illustration below compares monthly figures for a small business. It is not a tax schedule. Non-tax months and tax months have different disbursements, while expected and actual receipts differ by $16,000.
| Measure | Expected | Actual |
|---|---|---|
| Monthly receipts | $180,000 | $196,000 |
| Non-tax-month disbursements | $90,000 | $105,800 |
| Tax-month disbursements | $175,000 | $190,800 |
| Non-tax-month net change | $90,000 | $90,200 |
| Tax-month net change | $5,000 | $5,200 |
A 12-Month Small-Business Example
In both types of month, actual net change is $200 above expectations. The receipts and disbursements each differ from the forecast, so we should review both sides. Across 12 months, the difference is $2,400, or 0.3% in favor of the business.
Use Variances to Improve the Next Forecast
Excel SUMIF can total values that match “Expected” or “Actual,” making a quick comparison easier. We can ask whether customers paid later than planned, whether variable costs rose, or whether fixed-cost assumptions missed a bill. Comparing expected and actual results helps improve future projections.
Check whether a difference came from timing, a changed business decision, or a poor estimate. A late customer payment may shift cash into another month without changing total sales. Record the reason for each material variance before changing the next forecast’s assumptions.
Should We Use Excel or Forecasting Software?
A spreadsheet is a sensible starting point when the business needs a flexible model and can keep its inputs current. Excel templates can model income, expenses, cash balances, and best-, worst-, and expected-case scenarios. Charts and tables can display scenario comparisons at a glance.
In a 2025 AFP FP&A survey, 96% of finance professionals still relied on spreadsheets as their primary planning tool, while 23% regularly used AI in forecasting. Cash flow forecasting models in Excel can start with customizable categories and formulas. Templates can also include a starting date and forecast period.
Excel Templates for Cash Flow Forecasting
A cash flow forecast template in Excel should include a starting balance, income sources, the forecast period, fixed and variable expenses, and working formulas. Microsoft Excel templates can show income, expenses, cash balances, and scenario charts. Coefficient offers a 12-month template for Excel and Google Sheets, with monthly categories, automatic calculations, and charts.
Before using a file, check that its formulas match the business’s time buckets and cash lines. Charts can help us compare a best case with an expected or worst case. They cannot fix an incorrect starting balance or missing payment.
When Dedicated Software Adds Value
Dedicated tools can help when teams need live data, shared reviews, or more detailed predictions. Tesorio offers invoice-level machine-learning payment predictions and a 13-week forecast with live ERP synchronization. Cube works in Excel and Google Sheets with scenarios, rolling budgets, and data consolidation.
| Tool | Platform | Stated forecasting feature | Capability to assess |
|---|---|---|---|
| Excel | Microsoft spreadsheet | Templates, scenarios, charts | Formula control and data updates |
| Coefficient | Excel and Google Sheets | 12-month template and charts | Monthly category fit |
| Tesorio | ERP-connected platform | Invoice predictions and 13-week view | Payment prediction detail |
| Cube | Excel and Google Sheets | Scenarios and rolling budgets | Data consolidation needs |
Pigment connects profit and loss, balance sheet, and cash planning. Workday Adaptive Planning, Float, and HighRadius also serve planning needs. We can compare tools by checking data integration, invoice-level predictions, scenario handling, rolling updates, and actual-versus-forecast tracking. Select tools by the data connections and review process the team needs, not by feature count alone.
What Can We Do When a Forecast Shows a Shortfall?
A projected shortfall is a prompt to act while the business still has choices, not a reason to wait for the bank balance to fall. Early warning can give us time to build reserves or postpone a major purchase. Respond while there is still time to change a payment or spending decision.
A 13-week rolling forecast updated weekly can reflect current business conditions more closely than a monthly forecast refreshed at month-end. Small businesses often benefit from weekly short-term updates and monthly reviews of longer-range projections. We can review more often when cash flow is irregular or actual results keep diverging.
A cash gap is easier to manage when we name the largest risks and assign a response before the due date.
- Confirm the largest upcoming payments and their due dates.
- Follow up on overdue customer invoices.
- Review discretionary spending for items we can delay.
- Prepare a downside scenario with lower receipts or higher costs.
For each action, name an owner and set a decision date. That lets us track whether the response changed the forecast before the cash need arrives. Assign each response to an owner and a decision date so the forecast leads to action.
Conclusion
We do not need a perfect model to make a better-informed cash decision. A useful forecast is a living estimate based on current cash data and clear assumptions, not a promise of exact results. Its value comes from updates that reflect what the business knows now.
Start with the next forecast period, reconcile the opening balance, and enter the largest expected receipts and payments with their dates. That gives us a clear first view without building more detail than we can maintain. Set a date for the first forecast review and compare the projected balance with what actually happened.